







 Add Us On Google

Disclosure: This research was conducted by FinanceBuzz and sponsored by Wells Fargo. Survey administration, analysis, and editorial development were performed by FinanceBuzz.
There's something special about your first relationship with a bank. Between financial independence, shared trust, and a mutual goal of making account balances trend upward, Americans have a deep and loyal relationship with their banks.
On average, Americans have had their bank accounts for 12.1 years, longer than their relationships with their cell phones, cars, and homes. 80% say they're genuinely happy with their bank. Their loyalty comes from trust, satisfaction, and features they value, delivered through their banking app and the branch. That said, many are also leaving useful features unused.
Our research team at FinanceBuzz, in a sponsored content partnership with Wells Fargo, surveyed 2,000 U.S. adults on their banking histories, relationships, and preferences to find out the top reasons people stay with their banks, how willing they'd be to switch, and what drives the banking loyalty that keeps Americans with their banking partners.
Key findings
- Banking relationships have longevity: On average, Americans stay with their primary bank for 12.1 years, outlasting the typical cell phone, car, and, in many cases, their home.
- Loyalty comes from satisfaction: 80% say they're satisfied with their bank.
- Preference for apps: 65% say they prefer a great app vs. branch access, but 77% of banking customers still say branch and ATM access are important when choosing a bank.
- One feature could tip the scales: 59% of banking customers say a single feature could make them consider switching banks.
Americans stay with their banks longer than almost anything else
To start our research, we asked Americans how long they've been with their primary banks (defined as their primary checking accounts, though we realize some split savings accounts to other institutions).
On average, Americans have been with their primary bank for 12.1 years, and 15% have been with their bank for more than 20 years. This makes banks, on average, one of the longest relationships Americans have, and longer than the average tenure of a cell phone (3.4 years), car (8.4 years), or home (12.0 years).
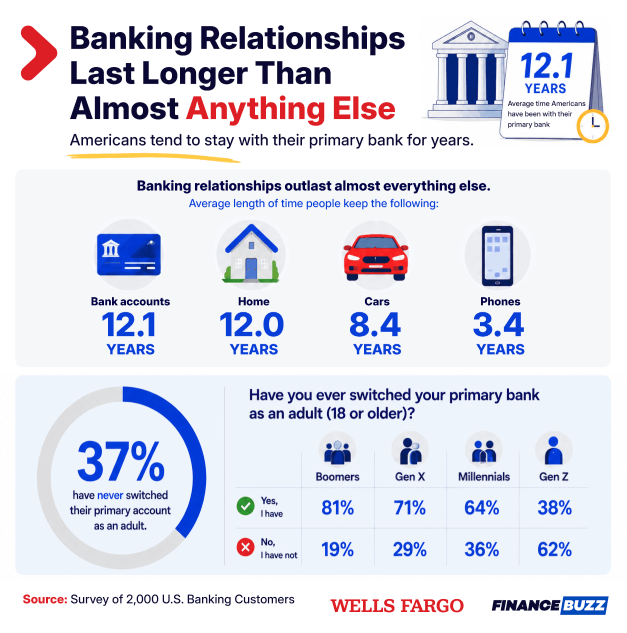
On the other side of the coin, 63% of Americans have switched their primary bank account as an adult (meaning 37% have not), and these numbers fall steadily by generation: 81% of Baby Boomers, 71% of Gen X, 64% of Millennials, and just 38% of Gen Z say they've switched their primary bank accounts as adults.
How Americans choose their bank: family, friends, and features
Americans find their way to a bank in different ways. For many, it starts with a parent opening their first account. For others, it's a choice they make on their own.
When asked how they chose their current primary bank, 43% said a family member or friend banked there or recommended it, while 25% said they made an independent choice based on their own research. Another 18% went with the most convenient option, and 8% signed up for a promotional offer or bonus.
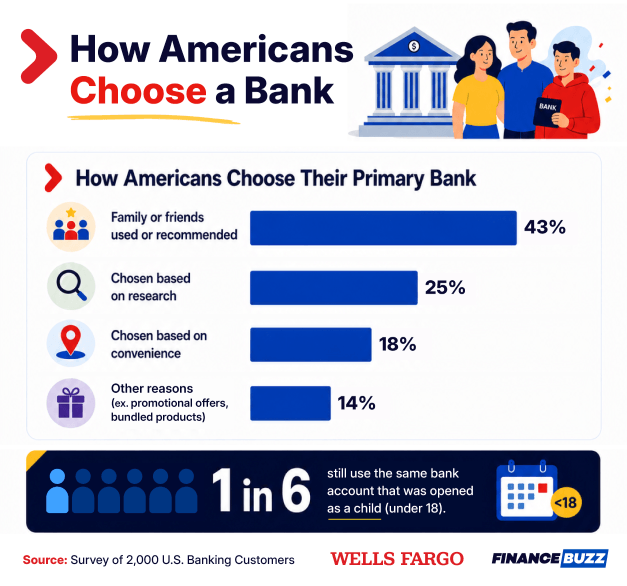
Overall, 16% (roughly 1 in 6) of Americans currently have a primary checking account that was opened for them as a child (under 18), rising to 39% among Gen Z respondents.
| Age when U.S. adults opened their primary checking account | ||||
| Baby Boomer | Gen X | Millennials | Gen Z | |
| 17 or younger | 2% | 7% | 14% | 39% |
| 18-25 | 15% | 24% | 41% | 57% |
| 26-35 | 12% | 21% | 34% | 4% |
| 36-45 | 21% | 26% | 11% | - |
| 46-55 | 20% | 19% | - | - |
| 56+ | 30% | 3% | - | - |
Starting a banking relationship early can be useful for building financial habits and learning how to manage money, and many banks offer useful tools for parents to co-manage finances and maintain some guardrails on their teen's spending.
What different generations value in a bank
On the fundamentals, Americans agree more than the generational-divide framing would suggest.
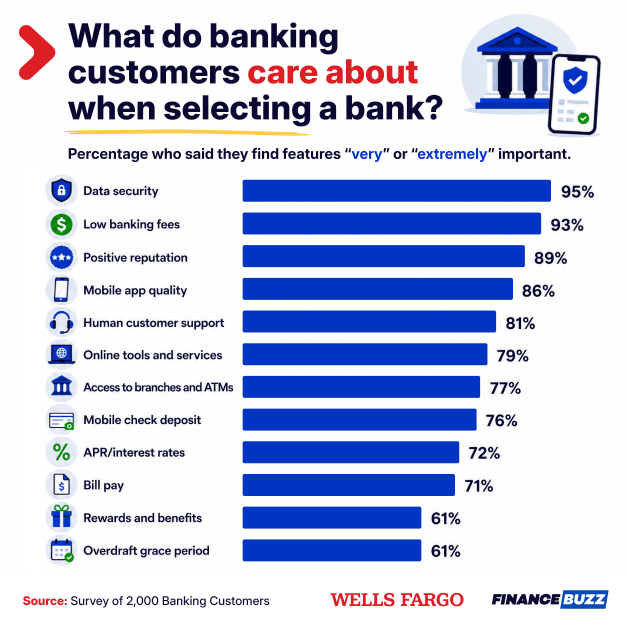
Data security is the top priority across the board at 95%, followed by low banking fees (93%) and a positive reputation (89%). Asked to name the single factor that should matter most when choosing a bank, every generation picks data security first.
Those fundamentals are also the starting point for choosing a checking account. Wells Fargo, for example, offers four checking accounts: Clear Access Banking, Everyday Checking, Prime Checking, and Premier® Checking, giving customers options that align with different banking preferences. Prime Checking and Premier Checking also earn interest on balances.
Most Americans rate the everyday basics as important too: 86% say mobile app quality is very or extremely important, 77% say the same about branch and ATM access, and 76% say that about mobile check deposits. Every Wells Fargo checking account comes with access to Wells Fargo Online® and the Wells Fargo Mobile® app, where eligible customers can deposit checks through the app, along with the bank's branch and ATM network for anything they'd rather handle in person.
Where generations actually diverge is in everything built on top of the app:
| Percentage who say banking features are very or extremely important in choosing a bank | ||
| Feature | Baby Boomers | Gen Z |
| Mobile app quality | 75% | 91% |
| Rewards and benefits | 50% | 73% |
| Built-in P2P payments (e.g., Zelle®)1 <p class="">Zelle and the Zelle marks used herein are trademarks of Early Warning Services, LLC.</p> | 39% | 61% |
| Credit score monitoring | 34% | 56% |
| Built-in budgeting/spending tracker | 12% | 39% |
| Savings goal tools | 15% | 36% |
The pattern is consistent. Boomers evaluate a bank on whether it safely holds money and doesn't overcharge. Gen Z evaluates it on whether it actively helps them manage money. Younger Americans want the bank to do something with the money, not just keep it.
For the most part, their behavior backs that up. 28% of Gen Z use budgeting or spending tracking tools in their banking app multiple times per month, versus 12% of Boomers. 28% of Gen Z check their credit score through their bank, versus 12% of Boomers. 44% of Gen Z use Zelle®1 <p class="">Zelle and the Zelle marks used herein are trademarks of Early Warning Services, LLC.</p> or a built-in peer-to-peer tool multiple times per month, versus 19% of Boomers.
Why Americans stay: satisfaction and the features they value
According to our survey data, 54% of Americans say they've never seriously considered changing their current primary bank account.
When asked why they stay, about half (51%) said they're genuinely happy with their bank. Other common reasons point to what builds that satisfaction:
- 28% have never had a serious problem
- 27% have all their bills on autopay there
- 25% find the branch and ATM locations convenient
- 19% cite good customer service
- 11% have multiple products with the bank
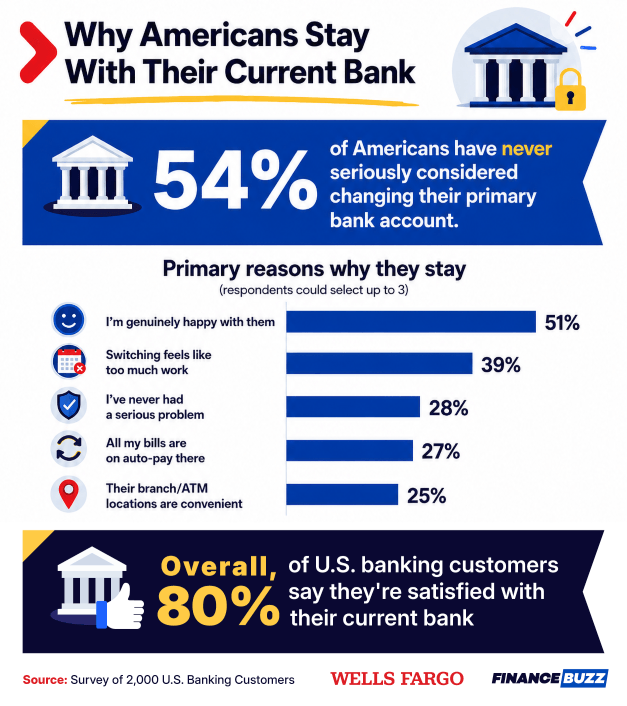
Convenience shows up again and again in why people stay. A bank that fits into everyday life, through autopay, nearby branches and ATMs, and helpful service, is one people don't have a reason to leave.
Wells Fargo, for example, pairs its digital tools with a vast, nationwide branch and ATM network, so customers can bank in the way that best suits their needs: in person, online, through the app, or all three. For the 11% who stay because they have multiple products with their bank, Wells Fargo offers a range of checking accounts for different needs and life stages, and its Prime Checking and Premier Checking also offer relationship benefits, including eligible banking-service fee waivers and discounts, subject to account terms.
How Americans use their banks
When it comes to modern banking, it's no surprise that most banking takes place online. As part of our survey, we asked banking customers how often they do specific things with their bank, and the results were largely digital-leaning.
96% of banking customers regularly (multiple times a month) check their account balances, and 95% access their bank online or through an app. Compare this to more traditional banking activities, like getting cash from an ATM (31%) and visiting branches (12%), and it's clear that digital banking is here to stay and works hand-in-hand with in-branch access like that offered by Wells Fargo.
When asked about the most important features in selecting a bank, 77% of banking customers say access to branches and ATMs is very or extremely important, though only 12% say they visit a branch multiple times per month.
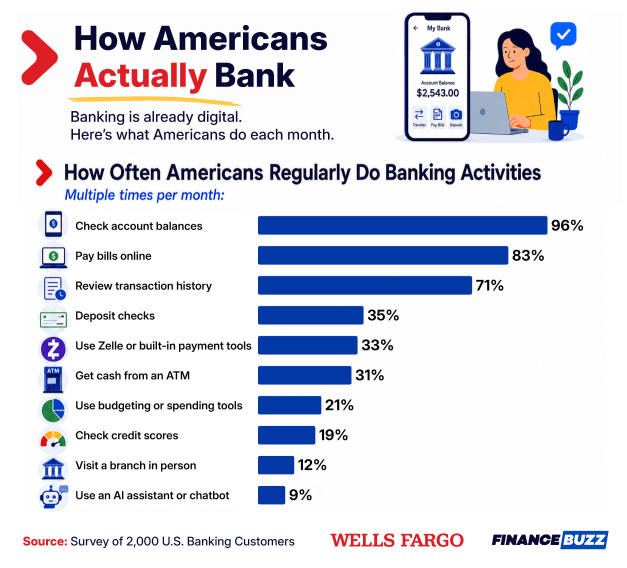
Some interesting data, though, exists in the usage rates for specific banking features. 1 in 3 banking customers say they use their bank to send peer-to-peer payments via Zelle®1 <p class="">Zelle and the Zelle marks used herein are trademarks of Early Warning Services, LLC.</p> or a similar tool. 23% use their bank to access early paycheck or direct deposit features, 21% use digital budgeting tools, 19% check their credit score through their bank, and roughly 1 in 10 (9%) use a relative newcomer to digital banking, AI insights.
Part of this is due to its relative youth and product adoption, but also because many banks don't yet offer AI banking solutions within their apps and online platforms. Overall, 52% of customers said they'd find AI insights valuable for managing their finances.
Some national banks do offer these insights, however. For example, Fargo®, Wells Fargo's virtual assistant, can help customers forecast their future balance, keep tabs on subscriptions, view spending insights, and transfer funds. Wells Fargo customers can also use Zelle®1 <p class="">Zelle and the Zelle marks used herein are trademarks of Early Warning Services, LLC.</p> within the Wells Fargo Mobile® app to send money to people they know and trust.
Digital banking leads daily usage, while branch and ATM access remain important features for many customers
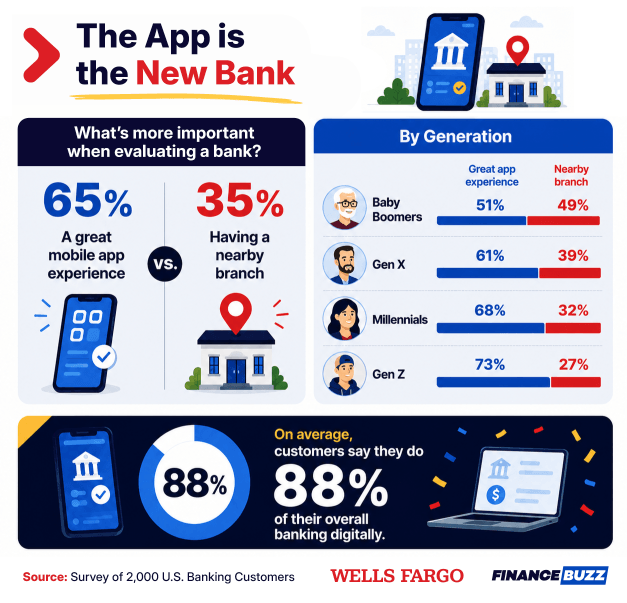
Asked directly what matters more when evaluating a bank, a great app or a nearby branch, 65% choose the app. That preference holds across every generation, including the one you'd least expect: 51% of Boomers pick the app over the branch, rising to 61% of Gen X, 68% of Millennials, and 73% of Gen Z. On average, banking customers said 88% of their banking was done on the screen. While digital banking leads in daily usage, branch and ATM access remain vital.
Returning to our example bank, Wells Fargo's mobile and online banking covers the high-frequency behaviors this data identifies: balance checks, bill pay, transfers between accounts, mobile check deposit, and transaction review. Zelle®1 <p class="">Zelle and the Zelle marks used herein are trademarks of Early Warning Services, LLC.</p> is built in for sending money to people you know, which a third of Americans do through a bank-native peer-to-peer tool multiple times a month.
A strong app doesn't replace the branch, though. Even as the preference for a great app climbs from 51% of Boomers to 73% of Gen Z, the share who call branch and ATM access very or extremely important barely moves, staying between 74% and 78% in every generation.
That's where a large branch network matters. It gives customers a place to deposit or withdraw cash, get face-to-face help, or handle something an app can't, without changing how they bank day to day. With more than 4,000 branches and 11,000 ATMs, Wells Fargo is set up for customers who want both, so they can bank on their phone or online most days and in person when they need to.
What would actually make someone switch
Most Americans aren't looking to leave. 64% say they're unlikely to switch banks in the next 12 months, rising to 71% among those who are genuinely happy with their bank. And 41% say no single feature would be enough to make them switch.
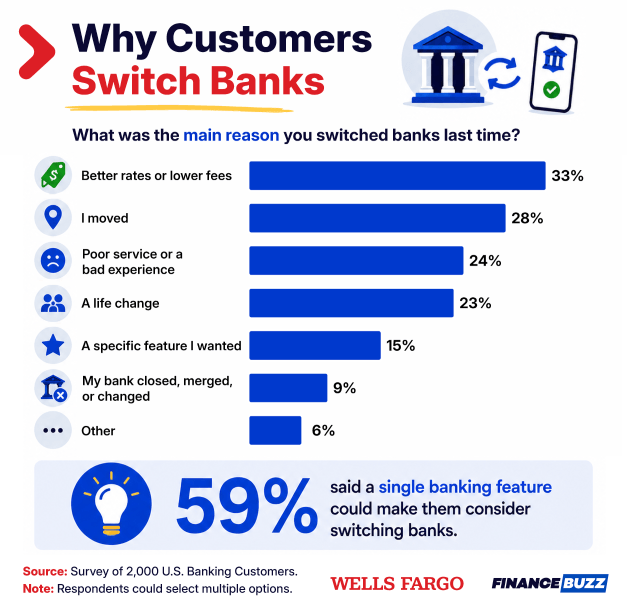
That said, loyalty isn't automatic. 59% say a single feature could make them consider switching.
When people who have switched banks were asked why, better rates or lower fees topped the list (33%), followed by moving (28%), poor service (24%), a broader life change (23%), and a specific feature they wanted (15%).
When people do switch, it's often because their life changed, not because their bank let them down. Among Americans who've switched, 52% cited moving, a life change, or their bank closing or merging, and 39% gave only those reasons.
Once customers have thought about switching, however, some features can create change:
- Peer-to-peer payments. A third of Americans (33%) use Zelle®1 <p class="">Zelle and the Zelle marks used herein are trademarks of Early Warning Services, LLC.</p> or a bank-native P2P tool multiple times a month, rising to 44% of Gen Z. 53% call built-in peer-to-peer options very or extremely important when choosing a bank.
- Early paycheck access. 23% of Americans access early paycheck or direct deposit features multiple times a month. Half say they never do.
- Bill pay and mobile deposit. 83% pay bills online multiple times a month and 76% call mobile check deposit very or extremely important, making these table stakes rather than differentiators.
The gap between the 23% of Americans who use early paycheck access and the half who never do may partly be an awareness gap. With features like Wells Fargo's Early Pay Day, eligible Wells Fargo customers may be able to access eligible direct deposits up to two business days early. Early availability is not guaranteed and may vary between pay periods. People often discover early payday options only when they look for them.
How to actually evaluate the bank you already have
You don't have to switch banks to get more out of one. Most of the value on the table comes from checking things nobody checks. Some tips from our experts:
- Turn on the tools you already have. 51% of Americans have never used their bank's budgeting or spending tracking tools, and 40% have never checked their credit score through their bank. These are usually included at no cost. Wells Fargo customers, for example, have access to LifeSync® for goal tracking and Fargo® for questions about spending and balances.
- Find out whether you have early paycheck access. Half of Americans say they never use it. Check before your next tight week, not during one.
- Review the account you opened when you were younger. If a parent opened your account, or you opened it at 17, it's worth confirming the account still fits your needs today.
- Separate hassle from value. 63% of Americans say switching would be too much hassle, but they may be overestimating the lift. Many banks offer tools to help transfer accounts, set up bill pay and automatic payments, and consolidate accounts.
Methodology
FinanceBuzz surveyed 2,000 U.S. banking customers via Prolific in July 2026. This study was conducted independently by FinanceBuzz as part of a sponsored content relationship with Wells Fargo. Findings and analysis were developed by FinanceBuzz's research team.
Several questions were asked on standard Likert scales, including questions about likelihood to switch banks and importance of banking features. Some questions were only asked of relevant respondents (for instance, questions about why they switched accounts were only asked to respondents who indicated they've switched in the past).