







 Add Us On Google

Remember when paying extra for convenience felt like an occasional splurge? For millions of Americans, it's now part of the weekly budget.
According to a recent survey by FinanceBuzz in partnership with Bank of America, 85% of consumers pick up takeout at least monthly, 63% pay for food delivery, and 50% get groceries delivered. The habit is growing too. 52% say they spend more on convenience than they did five years ago, compared with just 25% who say they spend less.
There's nothing inherently wrong with paying to save time. The problem starts when convenience becomes so routine that you stop asking what you're actually getting for the extra money.
A delivery fee might save an hour of grocery shopping. It might also cost more than a five-minute trip to the store. A membership might eliminate repeated fees, but only if you're using it often enough to justify the subscription.
The difference comes down to what the convenience replaces. Here's how to tell the difference.
5 times paying for convenience actually saves you money
The numbers point to a bigger shift in how Americans shop, but frequency alone doesn't reveal if the spending is smart. How often you order, what you're buying, and which fees come with the service all factor into the decision. These five examples show where convenience spending could make practical financial sense when you look beyond the sticker price.
1. Choosing pickup over delivery
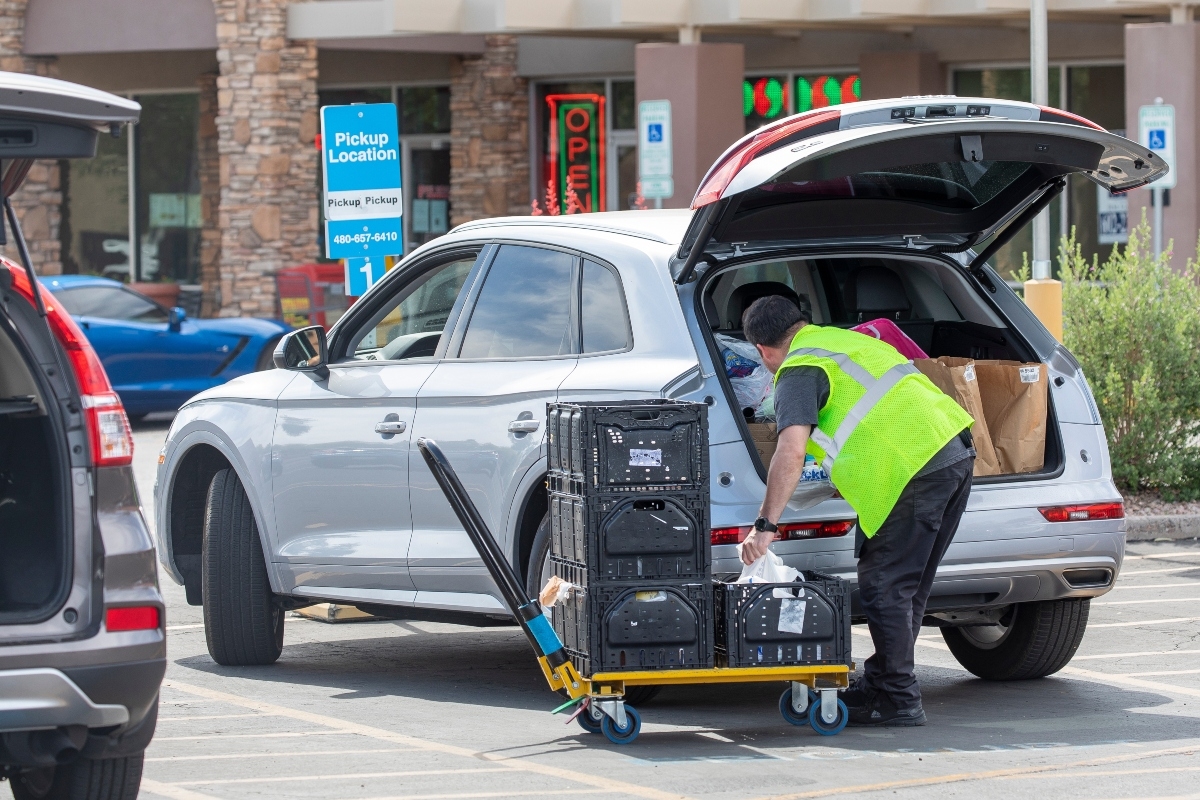
On a typical $100 grocery basket, shoppers said they'd accept up to $11.44 in extra cost to have someone shop for them and pick it up themselves, and up to $15.87 to have the order delivered. Delivery is worth more to people, but not by much: about $4.43 on a $100 order.
The tip is where the gap widens. Grocery delivery tips average $11.17, and pickup skips that entirely. So the delivery premium most people are actually paying is larger than the one they say they'd accept.
The savings become more useful when pickup fits into a trip you're already making. You could place the order from home, choose a convenient collection window, and skip walking the aisles. For planned grocery shopping, that keeps most of the convenience and more of the money.
2. Closing the app once you see the total cost
68% of consumers have abandoned a delivery order after seeing the full cost with fees. The reason is easy to understand. A meal might seem reasonably priced while you're browsing but then look very different once delivery charges, service fees, taxes, and tips are added.
Consider a $25 meal that reaches $40 at checkout. You're now paying $15 more for the convenience of having it delivered. That doesn't automatically make the order a bad deal, especially on a busy night, but it gives you a better basis for deciding.
The full total is the number to be mindful of. If the final price feels too high, closing the app before paying keeps the extra $15 in your account. You can also compare the delivery total with pickup before deciding. That quick check could prevent convenience fees from quietly becoming part of your regular food budget.
3. Use rewards to save more on convenience
Credit card rewards can reduce the cost of convenience as long as they align with how you spend. For example, the Bank of America® Customized Cash Rewards credit card lets you earn 6% cash back for the first year in the category of your choice (3% after that), and online shopping and dining (including takeout and delivery) are among the categories you can choose. You can change your chosen category once per calendar month through online banking or the mobile app.
Additionally, you'll automatically earn 2% cash back at grocery stores and wholesale clubs. Those reward rates apply to the first $2,500 in combined purchases each quarter in the choice category and at grocery stores and wholesale clubs, then unlimited 1% thereafter.
4. Using delivery for the full haul only
Among people who order groceries for delivery or pickup, 43% say it costs them more overall, while 34% say it saves them money, and 23% say it makes little difference. Those numbers show that convenience doesn't have a universal value. The calculation changes depending on what you're buying and how much time the trip would take.
37% of shoppers say their orders are typically big grocery trips. They're the strongest case for paying for convenience. A full weekly shop could take an hour or more once you factor in parking, aisles, checkout, and loading the car. Paying to eliminate that chore makes sense.
31% say their orders are typically top-off runs, and the calculation changes again. Paying a delivery fee for a few forgotten items might easily cost more than the short trip to the store. That's especially true when the basket isn't large enough to spread the fee across several purchases. Convenience works best when it replaces a substantial errand.
5. Buying the membership that matches your usage
Frequent orders can make individual convenience fees harder to justify. A membership may bring those costs under control, but only if you use it often enough. 37% of consumers bought a membership after realizing how much they were paying in per-order fees.
Amazon Prime shows why usage matters. 74% of consumers pay for Prime, and 86% of Prime subscribers use it multiple times a month. Walmart+ has the same 86% multiple-use rate. Frequent users get more chances to spread the membership cost across purchases they were already planning to make.
3 times it's a total trap
Convenience becomes expensive when you're paying to eliminate a cost that was already tiny. And the problem usually isn't one delivery order or one subscription. It's repetition. A $5 fee feels insignificant on its own, but several weekly charges can quietly add up to hundreds of dollars over a year. Here's where convenience spending deserves a harder look.
1. Delivery from a mile away
57% of consumers have ordered delivery from a restaurant within one mile of home. That doesn't automatically make the purchase foolish. Someone working late, caring for a child, dealing with bad weather, or facing mobility challenges may place a real value on having food brought to the door.
The financial calculation changes when delivery simply replaces a short, inexpensive trip that you could easily take. A restaurant one mile away might take only a few minutes to reach, yet the order could attract a delivery charge, service fee, and tip.
That said, it might be worth it for you and your situation, and if it is, there's absolutely nothing wrong with that.
2. The fee limit nobody enforces
Our survey found that the average person will accept about $9.49 in delivery fees before deciding to go pick the order up themselves. The median is $7, and the single most common answer is just $5. The problem is that the delivery fee isn't usually the entire convenience premium.
The average tip on food delivery is another $8.26. Add those together and you're near $18 before accounting for service fees, markups, or anything else that shows up at checkout.
A $15 premium on a busy night may feel reasonable if it saves an hour. Paying the same amount to avoid a nearby pickup is much harder to justify. The fee becomes a trap when you stop noticing it.
3. Memberships stacked on top of each other
The same 37% who made a smart membership decision also illustrate what happens when the decision isn't revisited. 21% pay for DashPass, 13% for Uber One, 11% for Target Circle 360, and 6% for Grubhub+, often alongside Prime, which many of them also hold.
Usage explains why some memberships work better than others. 84% of DashPass subscribers use it multiple times a month, so that membership is working. The picture changes with Target Circle 360, where only 61% reach that frequency, and Grubhub+, where the figure falls to 58%.
A five-minute audit of your memberships might uncover subscriptions that no longer earn their keep. Check which ones you still use and which ones simply carried over from a promotional sign-up. You may find $100 to $200 in annual spending going toward services you barely use.
Bottom line
Convenience spending works when it replaces a meaningful cost, such as the time required for a large grocery trip. It becomes a trap when you're paying for something that was already cheap or easy to handle yourself. 52% of consumers now spend more on convenience than they did five years ago (compared with 25% who spend less), making those decisions increasingly important to everyday budgets.
The best test is to look at what the fee actually buys you. Paying $15 to deliver a meal from a restaurant a mile away is harder to justify than spending $15 to eliminate an hour-long grocery trip. Before paying, compare the convenience fee with the time, effort, and cost you're avoiding.
And make sure the way you're paying for convenience makes the most of every dollar. Returning to our example card, the Bank of America® Customized Cash Rewards credit card can add cash back to the purchases you already make. And that 6% you can earn during your first year on your choice category can make a substantial difference to your budget and make up for some of what we pay for convenience.