





 Add Us On Google

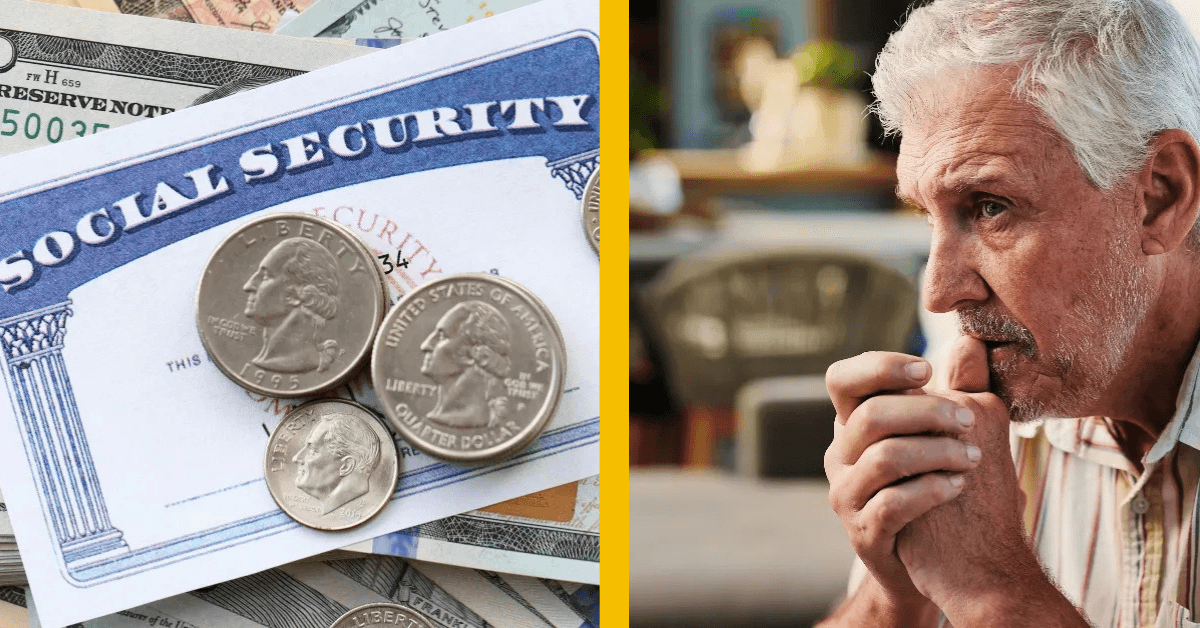
Social Security beneficiaries could be heading toward a history-making raise in 2027.
Current projections suggest next year's cost-of-living adjustment (COLA) may mark the sixth straight year of at least a 2.5% increase, something not seen since 1997. But the official number won't be known until the Social Security Administration announces it in October 2026.
And even if the projected increase comes through, a bigger Social Security check doesn't necessarily mean seniors will experience benefits and feel richer.
Here's what's driving the latest estimates and why many seniors may still feel squeezed.
Get a protection plan on all your appliances
Did you know if your air conditioner stops working, your homeowner’s insurance won’t cover it? Same with plumbing, electrical issues, appliances, and more.
A home warranty from Choice Home Warranty could pick up the slack where insurance falls short.
For a limited time, you can get your first month free with a Single Payment home warranty plan.
What is the Social Security COLA?
The Social Security COLA is an annual adjustment designed to help benefits keep up with inflation. Without it, rising prices would steadily reduce retirees' purchasing power.
COLAs are typically announced each October and take effect in January of the following year. The adjustment is based on inflation as measured by the Consumer Price Index for Urban Wage Earners and Clerical Workers, or CPI-W.
How the COLA is calculated
Since 1975, Social Security has used the CPI-W to calculate annual COLAs.
The SSA compares the average CPI-W readings for July, August, and September with the average from the same three months of the previous year. The resulting percentage, rounded to the nearest tenth, determines the COLA.
That means the 2027 increase is still a moving target. August's CPI-W has now been released, but September's reading is still needed before the calculation can be completed. The SSA is expected to announce the official 2027 COLA on Oct. 14.
The 2027 COLA may make history
If current projections hold, 2027 could mark the sixth consecutive year in which Social Security benefits increased by at least 2.5%. The last time that happened was from 1988 through 1997, nearly 30 years ago.
But there's an important catch: A history-making COLA would be a reflection of elevated prices, not necessarily a sign that retirees are getting ahead financially.
If you’re over 50, take advantage of massive discounts and financial resources
Over 50? Join AARP today— because if you’re not a member you could be missing out on huge perks. When you start your membership today, you can get discounts on things like travel, meal deliveries, eyeglasses, prescriptions that aren’t covered by insurance and more.
Start your membership by creating an account here and filling in all of the information (Do not skip this step!) Doing so will allow you to take up to 25% off your AARP membership, making it just $15 the first year with auto-renewal.
Current estimates are higher than expected
Earlier in 2026, projections climbed as inflation and energy prices surged. Since then, estimates have come down.
Among the major published forecasts, Mary Johnson, an independent Social Security and Medicare policy analyst, has projected a 3.4% COLA, while The Senior Citizens League (TSCL) has projected 3.6%. AARP's published estimate is 3.5%.
Keep in mind that those numbers are projections, not promises. Two of the three CPI-W readings used to calculate the official COLA are now available, but September's reading could still move the final number.
At TSCL's projected 3.6% rate, the average benefit used in its analysis would increase by about $69.75 per month, from $1,937.53 to $2,007.28.
Retirees have already seen several large increases
The last five years have already produced unusually high Social Security adjustments. Benefits rose by 5.9% in 2022, 8.7% in 2023, 3.2% in 2024, 2.5% in 2025, and 2.8% in 2026.
The 8.7% increase in 2023 was the largest percentage jump in more than four decades, highlighting how severe inflation became after the pandemic period.
Energy prices helped push projections higher — then eased
Energy prices played a major role in the earlier upward revisions to 2027 COLA forecasts.
The conflict involving Iran and disruptions around the Strait of Hormuz sent oil and gasoline prices sharply higher during spring 2026. U.S. gas prices rose significantly between February and March, adding to inflation pressures.
But that wasn't a permanent one-way trend.
The Strait of Hormuz subsequently reopened as conditions eased in June, and oil prices fell sharply as markets anticipated a return of supply.
That easing in energy prices helped pull inflation and COLA projections back down from their earlier highs.
The latest BLS data show why energy remains important. In August, gasoline prices rose 3.9% from the previous month, while the energy index increased 2.1%. Over the past year, however, the energy index was still up 16.3%, with gasoline prices up 27.4%.
Retirement News: Almost 80% of Americans fear a retirement age increase — here’s the real reason why
Inflation is still running higher than the long-term average
The latest BLS report showed consumer prices rose 3.4% over the 12 months ending in August 2026. The CPI-W, which is the index that matters for Social Security's COLA calculation, increased 3.5% over the same period.
That's an improvement from some of the higher inflation readings earlier in the year, but it remains significant.
And because Social Security's COLA is based on a specific three-month period rather than a single inflation reading, the August number alone doesn't determine what beneficiaries will receive next year.
A larger COLA does not always mean more buying power
While larger checks sound encouraging, many retirees continue struggling with rising costs.
That's partly because inflation isn't evenly distributed. Housing, insurance, and health care can take up a larger share of an older household's budget, and those expenses don't necessarily move in line with the overall CPI.
Worse, COLAs are calculated on trailing inflation data. If prices accelerate after the COLA is set, beneficiaries generally have to wait until the next year's adjustment for another increase. That can leave retirees playing catch-up.
Social Security has lost purchasing power since 2016
The Senior Citizens League's 2026 Loss of Buying Power report offers a more recent look at the problem.
According to TSCL, Social Security benefits lost about 13.7% of their buying power from 2016 to 2026 and are now worth roughly 86 cents on the dollar compared with a decade ago.
TSCL estimates that benefits would need to rise by about 15.7% — or roughly $295.85 a month for the average beneficiary — to restore the purchasing power they had in 2016.
This estimate puts the potential 2027 COLA in perspective. Even a 3.4% to 3.6% increase could help, but it wouldn't erase years of lost purchasing power.
Get instant access to hundreds of discounts
Over 50? Join AARP today— because if you’re not a member you could be missing out on huge perks like discounts on travel, dining, and even prescriptions.
Get 25% off membership — just $15 for your first year with auto-renewal — and a free gift if you join today.
The CPI-W problem: It's measuring the wrong people
The CPI-W was designed to track the spending patterns of urban wage earners and clerical workers.
But Social Security beneficiaries have different spending patterns. Older Americans generally devote more of their budgets to categories such as housing and medical care.
That's why some advocates have pushed for the Consumer Price Index for the Elderly, or CPI-E, to replace the CPI-W for Social Security's annual adjustment.
The CPI-E gives greater weight to spending categories that tend to matter more to older households. But it has not been adopted as the official measure for calculating Social Security COLAs.
Medicare premiums can eat into every COLA
For Medicare enrollees, the Social Security COLA isn't the only number that matters.
Medicare Part B premiums are generally deducted directly from Social Security benefits. If premiums rise in 2027, some of a beneficiary's COLA could effectively disappear before it reaches their bank account.
That means a projected increase on paper may not translate into the same increase in take-home benefits.
What a historic streak actually means for retirees
Six straight years of at least 2.5% COLAs is historically unusual. But the streak would also reflect the inflationary environment that made those increases necessary.
Larger checks can help retirees keep pace with higher prices, but they don't necessarily improve their financial position. If housing, health care, insurance, or other essential expenses rise faster than benefits, retirees can still lose ground.
Bottom line
The 2027 Social Security COLA may make history.
Current published projections put the increase around 3.4% to 3.6%, with TSCL at the high end and Mary Johnson at the low end. The latest August CPI-W reading came in at 3.5% year over year, but September's data will still factor into the official calculation.
So retirees shouldn't treat any projected dollar amount as guaranteed yet.
The SSA is expected to announce the official 2027 COLA on Oct. 14, 2026. Until then, the best way to think about the numbers is as a range of possibilities — not a promise of what's coming in your January check.
And even if the COLA reaches a six-year streak of 2.5% or more, a bigger check won't necessarily mean stronger buying power. Many retirees may need to supplement Social Security benefits with investment income or part-time work, since inflation in health care and housing continues outpacing the benefits many seniors receive.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.


- Huge discounts on travel, groceries, prescriptions and more
- Access to financial planning resources and health tools
- Join AARP and get 25% off with automatic renewal