





 Add Us On Google

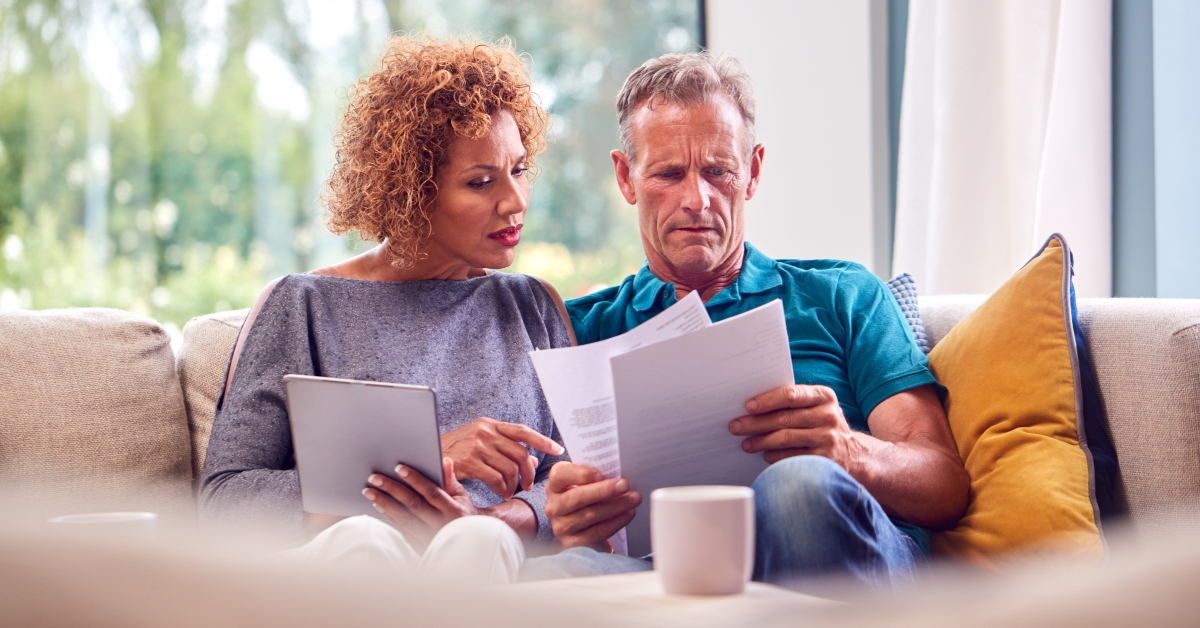
If you're nearing 85, you may be asking yourself, "After many years of retirement, is what's left in my nest egg enough?" To find your answer, you may be tempted to look at what others your age have in the bank, and we have the retirement plan data to help.
Here's what the average and median retirement balances look like for those in your age bracket, along with how to view them in a more realistic and useful way. You may be surprised to learn that you're not as far off as you thought you were!
Get a protection plan on all your appliances
Did you know if your air conditioner stops working, your homeowner’s insurance won’t cover it? Same with plumbing, electrical issues, appliances, and more.
A home warranty from Choice Home Warranty could pick up the slack where insurance falls short.
For a limited time, you can get your first month free with a Single Payment home warranty plan.
The average retirement account balance and what it means
The Federal Reserve's 2025 Survey of Consumer Finances cites $798,710 as the average household balance for the 75-and-older age bracket. This doesn't call out 85-year-olds specifically, but it's the most relevant data to learn from.
This number is much larger than the median amount, where half of households with retirement accounts have more and half have less. That median amount, just $257,000, may be more recognizable as a realistic balance for someone your age.
What "retirement accounts" really mean
The data also only counts those with retirement accounts, and about 45% of households in this age group even have retirement accounts.
The balances specifically counted in this survey include IRAs and workplace plans like 401(k)s, 403(b)s, and thrift savings accounts. While seniors at this age may still have money in defined-benefit pension plans, as well as housing equity, those assets weren't included in these numbers.
The data reflects the age and stage of retirement
It's quite normal to ask if account balances will last through the end of a lifetime, but someone at age 85 may naturally have less than someone at 65. There are good reasons for this.
First, an 85-year-old may have been spending from accounts for 20 years. Whether inflation and earnings kept up or not, it's reasonable to assume the money served its purpose — to support a healthy standard of living in retirement.
The Congressional Research Service identifies greater access to traditional pensions and possible exhaustion of earlier savings as potential reasons older households have lower retirement-account ownership rates.
If you’re over 50, take advantage of massive discounts and financial resources
Over 50? Join AARP today— because if you’re not a member you could be missing out on huge perks. When you start your membership today, you can get discounts on things like travel, meal deliveries, eyeglasses, prescriptions that aren’t covered by insurance and more.
Start your membership by creating an account here and filling in all of the information (Do not skip this step!) Doing so will allow you to take up to 25% off your AARP membership, making it just $15 the first year with auto-renewal.
Monthly income and expenses matter more than balance alone
You can use the Fed's median as an interesting benchmark, but your own monthly expenses matter more. Look at your essential costs for housing, health care, food, transportation, taxes, utilities, and debt payments, and compare them to dependable monthly income, including Social Security. This is a more helpful measure because it accounts for housing expenses and the cost of living for your area, not just the national average.
With Social Security acting as an ongoing income floor, pensions and annuity payments may reduce the amount a household needs to take out of retirement accounts. But Social Security is still the most common retirement-income source among households 65 and older.
Long-term care changes things quickly
If you've already started using long-term care services, you may have noticed the budgetary effects. Long-term care includes medical and nonmedical services, but most of it involves help with daily activities such as bathing, dressing, and eating. It is different from skilled nursing facility care.
Since Medicare and Medigap generally don't pay for nonmedical long-term care, you may be adding that to your budget and see the number rise as you age. The retirement account balance that seemed more than adequate just a few months ago can seem stretched when these new services are introduced.
Required minimum distributions (RMDs) aren't spending guidelines
A withdrawal guideline built for someone at the beginning of a 30-year retirement may change by the time someone reaches their mid-80s. That's why financial professionals often recommend reassessing the spending gap and remaining assets annually. The spending plan should account for remaining life expectancy, changing health needs, and the possible loss of a spouse.
RMDs are also a tax rule, and not a determination of what the household can sustainably spend. Traditional account withdrawals generally add taxable income. In addition to evaluating after-tax income alongside Social Security, retirees should consider whether they need to spend all of their RMDs. If they don't truly need the money, they can withdraw without consuming all of it.
Retirement News: Almost 80% of Americans fear a retirement age increase — here’s the real reason why
Simplify your finances while you still can
If you haven't already, your mid-80s are a time to review your estate plans, beneficiary designations, end-of-life wishes, and account statuses. You may find you need one plan for now and another for when you or a spouse dies. Consider how each plan will be carried out with as little stress to your loved ones as possible.
Leave documents in a safe place where executors can access them, and distinguish between authorized account access and a trusted contact. A trusted contact cannot transact, but a financial power of attorney can grant decision-making authority. Knowing how each role can interact with your assets and carry out your plans is just as important as assigning those roles.
Bottom line
Reaching the age of 85 is something to celebrate, no matter the size of your retirement account. To assess whether you have enough for your lifetime, however, a proper annual check-in makes sense. Don't just compare your funds to the $257,000 median balance and ignore the smart moves for seniors.
Instead, look at your total income, assets, and shifting health care priorities, and decide how much you want to leave behind. For some at this age, there's a delicate balance between meeting your own needs and passing on wealth. A financial professional can help you weigh the options.
FAQs
Does having less than the median mean you're behind on retirement savings?
Not necessarily. Someone with a pension, low housing costs, and little debt may need less savings than someone with higher bills. The median is a comparison point, not a minimum requirement for a secure retirement.
What should you do if your retirement savings are running low at 85?
Start by comparing essential monthly expenses with dependable income to identify any shortfall. Review recurring costs and available assistance with food, utilities, and healthcare. A financial professional can help you assess withdrawals and plan for future care expenses.
Does Medicare cover long-term care at 85?
Medicare generally doesn't cover ongoing help with daily activities such as bathing, dressing, and eating. It may cover certain short-term skilled nursing services when eligibility requirements are met. Include potential long-term care costs in your retirement budget.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.








- Huge discounts on travel, groceries, prescriptions and more
- Access to financial planning resources and health tools
- Join AARP and get 25% off with automatic renewal