





 Add Us On Google

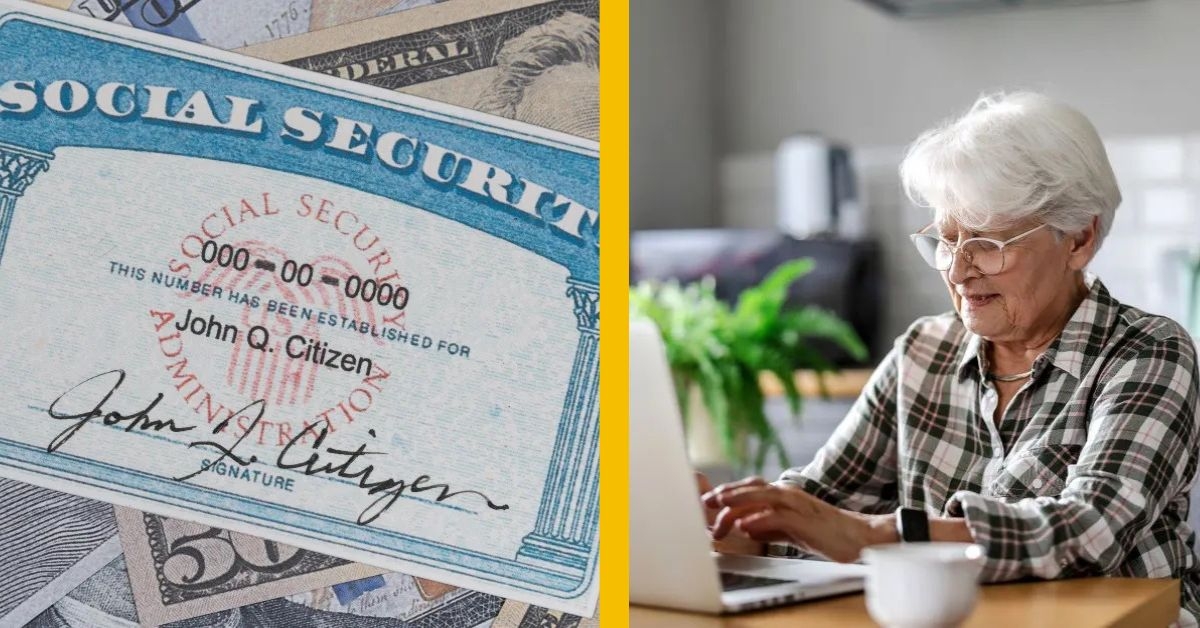
Qualifying for Social Security doesn't mean your benefit is untouchable. Even longtime beneficiaries who meet every work and age requirement can see their payments temporarily stopped or reduced under certain Social Security Administration (SSA) rules. Some situations suspend benefits entirely, while others simply result in a smaller monthly check.
Most of these situations aren't permanent, and they aren't new policy changes. They're longstanding SSA rules that catch people off guard because they don't expect them. And if a smaller check would squeeze your budget, there are ways that could put more money in your pocket when living on Social Security.
Get a protection plan on all your appliances
Did you know if your air conditioner stops working, your homeowner’s insurance won’t cover it? Same with plumbing, electrical issues, appliances, and more.
A home warranty from Choice Home Warranty could pick up the slack where insurance falls short.
For a limited time, you can get your first month free with a Single Payment home warranty plan.
Working while collecting benefits before full retirement age
If you claim retirement benefits before reaching full retirement age (FRA), which is 67 for people born in 1960 or later, your benefit can be reduced if you keep working and earn above certain limits. In 2027, the SSA will withhold $1 in benefits for every $2 you earn above $25,560 if you're under FRA all year, up from $24,480 in 2026.
In the year you reach FRA, the SSA will withhold $1 for every $3 earned above $67,920 (up from $65,160), counting only earnings in the months before you reach FRA. Once you reach full retirement age, there's no earnings limit. The earnings test applies to retirement and survivors benefits. Disability benefits follow separate work rules.
This isn't a permanent loss. The SSA recalculates your benefit at full retirement age to give you credit for months when payments were withheld, which could raise your monthly amount going forward.
If you expect to earn more than you estimated, or you start working after telling the SSA you wouldn't, let the agency know so it can adjust your payments.
An overpayment could reduce your benefits
If the SSA determines it paid you too much, by mistake or because of unreported changes in your situation, it's required by law to recover the money. For overpayment notices issued on or after April 25, 2025, the SSA's default is to withhold 50% of your monthly Social Security benefit until the debt is repaid, unless you pay it back within 30 days of the notice, according to the agency.
That means your check could be cut in half until the overpayment is resolved. (Supplemental Security Income overpayments are withheld at a separate, lower default rate of 10%.)
People whose overpayment notices came before that date generally keep their earlier withholding rate. If that withholding would cause a financial hardship, you can contact the SSA at 1-800-772-1213 to request a lower repayment rate, and you have the right to appeal the overpayment decision or request a waiver if you believe it wasn't your fault and you can't afford to repay it.
The SSA does not pursue collection while an initial appeal or waiver request is pending.
Incarceration for more than 30 days
Social Security retirement, survivors, and disability benefits are suspended if you're confined in jail or prison for more than 30 continuous days following a criminal conviction, per the SSA. You won't receive payments for the months you're confined, but benefits generally can be reinstated starting the month you're released, often by visiting a local Social Security office with proof of release.
This rule does not cut off dependents. Benefits paid to an eligible spouse or child on your record continue as long as they otherwise qualify. Supplemental Security Income (SSI), a separate needs-based program for people with limited income and resources, works differently: payments stop after one month of imprisonment and terminate entirely after 12 consecutive months, which means a new application is required to restart them.
If you’re over 50, take advantage of massive discounts and financial resources
Over 50? Join AARP today— because if you’re not a member you could be missing out on huge perks. When you start your membership today, you can get discounts on things like travel, meal deliveries, eyeglasses, prescriptions that aren’t covered by insurance and more.
Start your membership by creating an account here and filling in all of the information (Do not skip this step!) Doing so will allow you to take up to 25% off your AARP membership, making it just $15 the first year with auto-renewal.
Living outside the United States for too long
Moving abroad doesn't automatically end your Social Security benefits, but specific residency and reporting conditions apply, especially if you're not a U.S. citizen, according to the SSA. Payments could stop if you live in a country where the U.S. can't send payments, such as Cuba or North Korea, or if you don't return the questionnaires the SSA mails to beneficiaries abroad.
If you're not a U.S. citizen, payments could also stop after you've been outside the U.S. for six full calendar months, unless you meet an exception. The agency offers a Payments Abroad Screening Tool to help noncitizens check whether they qualify for continued payments.
If benefits stop under the six-month rule, they generally can't restart until you come back and stay in the U.S. for a full calendar month, according to the SSA. SSI is stricter: payments stop for any full calendar month you're outside the U.S., and they resume only after you've been back for 30 consecutive days, according to federal regulations.
Court-ordered garnishment for child support or alimony
Social Security benefits are generally protected from creditors, but federal law carves out exceptions for family obligations. Under Section 459 of the Social Security Act (42 U.S.C. 659), the SSA can withhold benefits to enforce child support or alimony obligations.
The garnishment amount is capped at the lesser of your state's limit or the federal Consumer Credit Protection Act limit, which the SSA says is generally 50% of benefits if you're supporting another spouse or child, or 60% if you aren't; those caps rise to 55% and 65% respectively if support payments are more than 12 weeks past due.
This isn't a suspension of eligibility. It's a reduction applied to an otherwise valid payment. The withholding continues as long as the court order remains in effect and typically ends once the underlying obligation is satisfied or modified by the court. If you believe the withholding is incorrect, contact the agency or court responsible for the support order, since the SSA generally cannot change the garnishment amount on its own.
Unpaid federal taxes or other federal debts
Beyond family-support obligations, the IRS can levy up to 15% of each Social Security payment to collect overdue federal tax debt, under the Taxpayer Relief Act of 1997, according to the SSA. Separately, the Treasury Department can withhold benefits to collect certain delinquent non-tax debts owed to other federal agencies under the Debt Collection Improvement Act of 1996.
Like child-support garnishment, this reduces a payment rather than eliminating eligibility, and it generally continues until the debt is resolved. If your benefits are being withheld for unpaid taxes, contact the IRS to discuss payment options. For other federal debts, contact the agency collecting the money to dispute the debt or discuss repayment arrangements.
Retirement News: Almost 80% of Americans fear a retirement age increase — here’s the real reason why
Voluntarily suspending your own benefit
Some beneficiaries choose to pause their own retirement benefit, often to earn delayed retirement credits, which can increase a future monthly amount by roughly 8% per year up to age 70, according to the SSA. This option applies only to retirement benefits.
If you've reached full retirement age but aren't yet 70, you can ask the SSA to suspend your payments. The suspension begins the month after you request it, and payments automatically restart the month you turn 70 if you haven't already asked to resume them sooner.
This is a choice, not a penalty, but it has ripple effects worth knowing. Other people receiving benefits on your record, such as a spouse, generally can't receive those benefits while yours is suspended (a divorced spouse is an exception). Medicare Part B premiums also can't be deducted from a suspended benefit, so you'd need to pay those separately to avoid a lapse in coverage, per the SSA.
Bottom line
A missed or reduced Social Security payment doesn't necessarily mean you've lost your eligibility. Many interruptions, from excess earnings to an overpayment recovery, are temporary and tied to specific, well-documented SSA rules rather than a loss of your underlying benefit. Reading any notice from the SSA carefully, and responding quickly, is often the fastest way to sort out what's actually happening.
If a payment doesn't arrive as expected, your my Social Security account can show payment and benefit-verification history, and the SSA's helpline at 1-800-772-1213 can clarify whether the issue is a suspension, a garnishment, or simply a processing delay.
Keeping contact information, direct deposit details, and any life changes updated with the SSA could help prevent some of these interruptions before they start. And if an interruption leaves your budget tight, a few options could help boost a fixed income.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.


- Huge discounts on travel, groceries, prescriptions and more
- Access to financial planning resources and health tools
- Join AARP and get 25% off with automatic renewal