






 Add Us On Google

Most retirees probably don't expect an old student loan to follow them into Social Security. Yet federal law allows the government to withhold part of certain Social Security benefits to collect defaulted federal student debt, a possibility worth factoring into your retirement plan if you're still carrying loans. The Education Department has temporarily paused these involuntary collections, but the underlying authority hasn't disappeared.
Hundreds of thousands of people near or already at Social Security claiming age have been estimated to hold federal student loans in default, and millions of older Americans still carry student debt. A future return of collections could seriously put an important source of retirement income back in play.
Here's what senior borrowers should understand before that possibility becomes a problem.
Now Available: The Definitive Guide to Retirement Income
Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.
That is exactly what The Definitive Guide to Retirement Income helps answer.1 <p class="">Investing in securities involves a risk of loss. Past performance is never a guarantee of future returns. Investing in foreign stock markets involves additional risks, such as the risk of currency fluctuations. Guides are provided by Fisher Investments. The publisher may be compensated when readers request a guide.</p> It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›
Defaulted federal loans can put benefits at risk
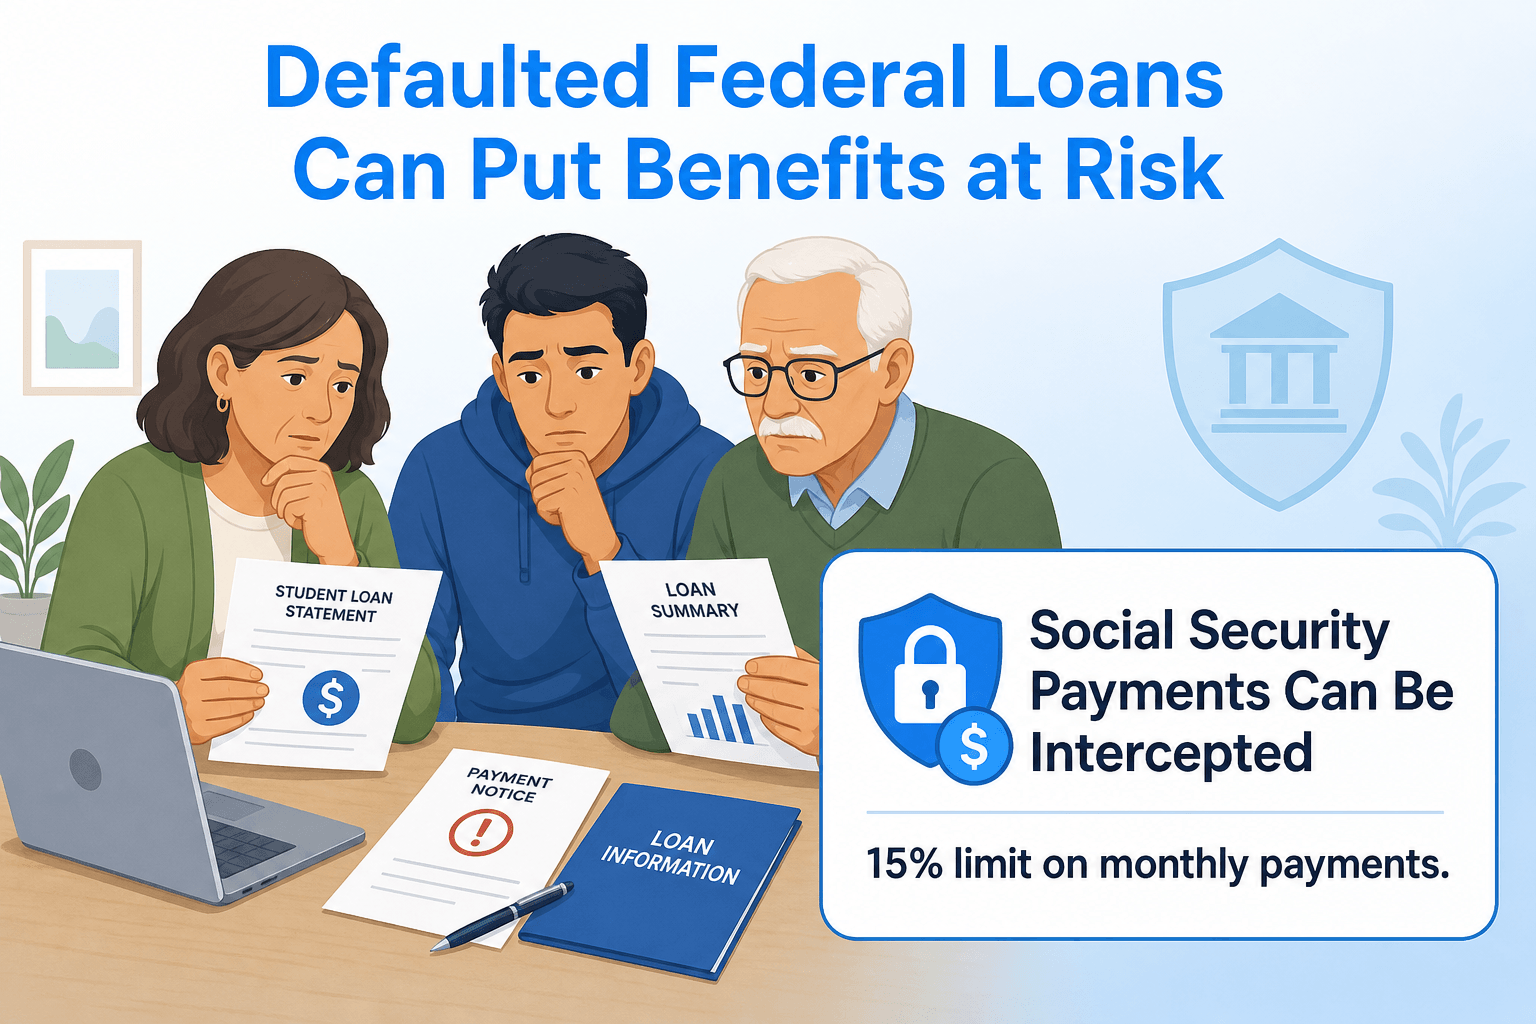
When a federal student loan goes into default, the government has collection powers that private lenders generally don't. Through the Treasury Offset Program, federal agencies can intercept certain government payments, including Social Security benefits, to collect delinquent federal debt. Treasury says a Social Security offset for federal nontax debt is limited to the lesser of 15% of the monthly payment or the amount above $750.
The Education Department currently has involuntary student loan collections through this program on hold, but it's a delay for now rather than a permanent elimination.
The $750 protection hasn't kept up with inflation
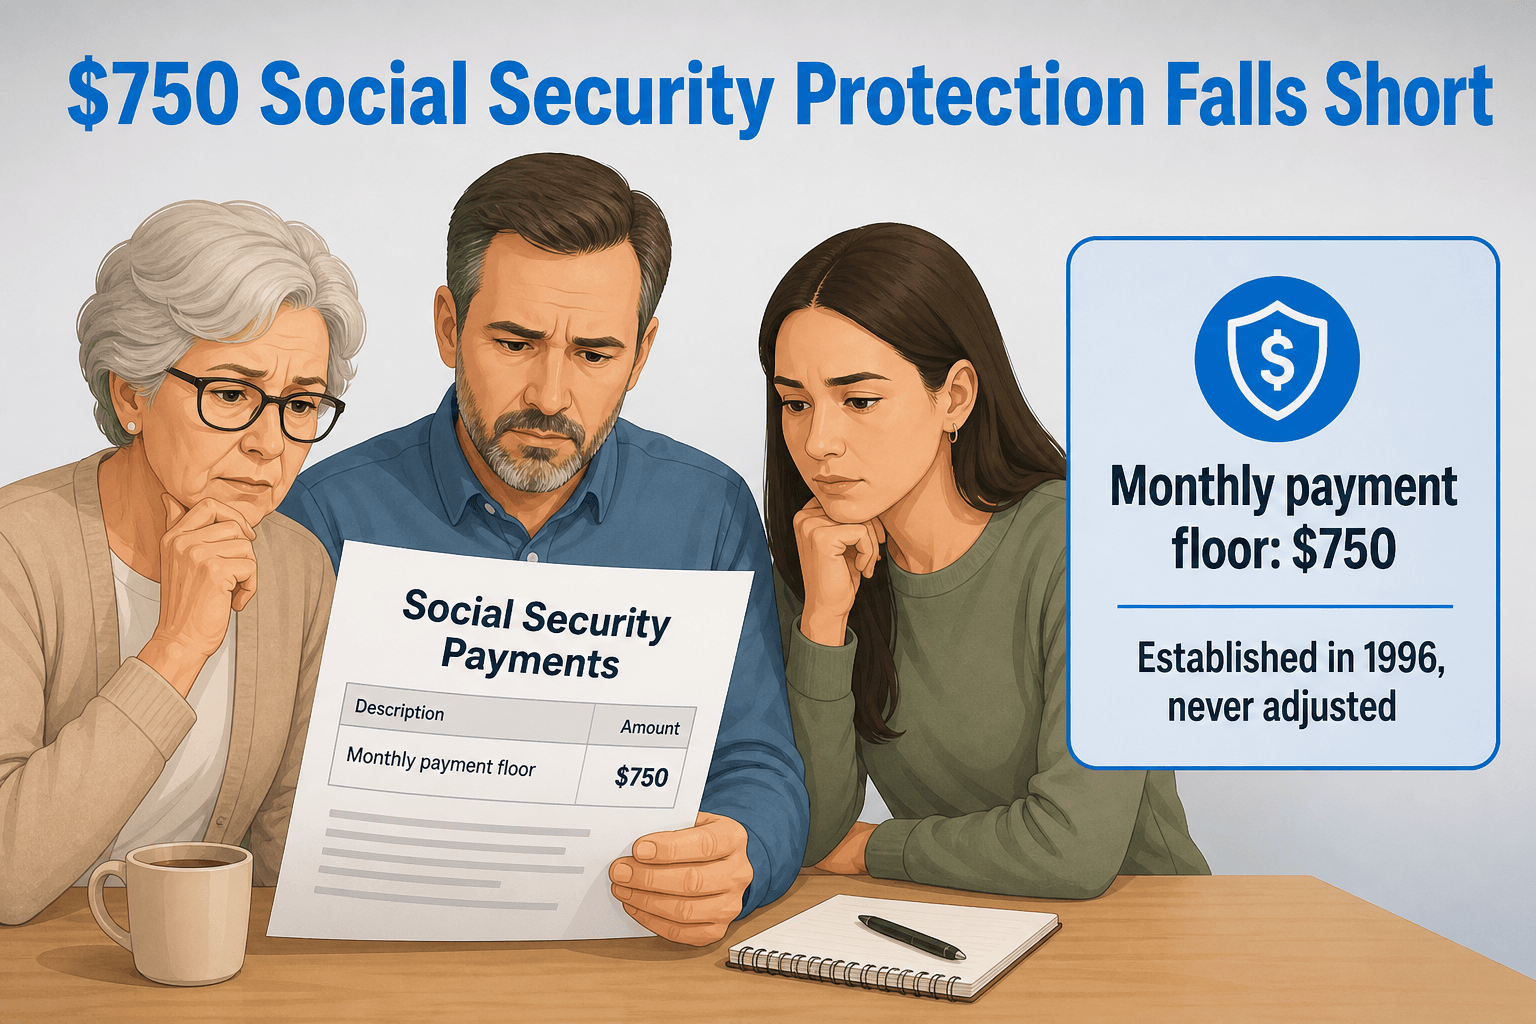
The law does protect part of every monthly Social Security payment, but the floor is surprisingly low. Only $750 per month is protected from this type of offset, a threshold the Consumer Financial Protection Bureau says was established in 1996 and has never been adjusted for inflation.
For example, someone receiving $1,500 per month could legally lose $225, leaving $1,275, while someone receiving $800 could lose no more than $50 because the payment can't fall below the $750 floor. That rule can hit especially hard when Social Security already covers essentials such as food, housing, prescriptions, and health care.
Hundreds of thousands of seniors have been exposed
The scale of the problem grew substantially before pandemic-era collection pauses. The CFPB found that the number of Social Security recipients whose benefits were reduced for student debt rose from roughly 6,200 in 2001 to about 192,300 in 2019, when the average amount collected reached $2,232 per year, or $186 per month.
The agency also estimated in 2025 that about 452,000 borrowers aged 62 and older had defaulted student loans and were likely receiving Social Security, while 2.7 million borrowers in that age group carried student loans as of 2023.
The financial consequences can be serious: CFPB research found that half of Social Security beneficiaries with defaulted student loans skipped a doctor's visit or didn't pick up a prescription medication because of cost, or both.
Released: The Definitive Guide to Retirement Income (Sponsor)
Most people spend their entire working lives focusing on one thing: growing a pile of money. Then they retire and discover the skill they actually need is close to the opposite. Turning that pile into steady income, year after year, through good markets and bad, without ever running out. It may be the least discussed and most consequential transition in personal finance, and plenty of otherwise careful investors walk into it with no real plan.
That is exactly what The Definitive Guide to Retirement Income helps answer.1 <p class="">Investing in securities involves a risk of loss. Past performance is never a guarantee of future returns. Investing in foreign stock markets involves additional risks, such as the risk of currency fluctuations. Guides are provided by Fisher Investments. The publisher may be compensated when readers request a guide.</p> It is a free guide from Fisher Investments covering what your retirement will really cost, where the cash flow should come from, and how much you can safely withdraw each year. Learn More Here ›
A proposed law could change the rules
Some lawmakers now want to eliminate the threat permanently. On Aug. 17, 2026, Sen. Bernie Sanders (I-VT) announced plans to introduce the Stop Social Security Garnishment Act of 2026, with Sens. Elizabeth Warren (D-Mass.), Ed Markey (D-Mass.), and Ron Wyden (D-Ore.) listed as cosponsors.
The proposal would prohibit the federal government from offsetting Social Security retirement and disability benefits to collect student loan debt, but as of early September, it hasn't been formally introduced or assigned a bill number. In other words, the announcement shows that Congress is paying attention to the issue, but borrowers shouldn't plan their finances around the proposal becoming law.
Borrowers can take action before collections return
Anyone with a federal student loan in default doesn't necessarily have to wait and see what happens. Federal Student Aid says loan rehabilitation can remove a loan from default after the borrower signs a rehabilitation agreement and makes the required payments; Direct Loan and FFEL borrowers generally need nine on-time payments within 10 consecutive months.
Once a loan is out of default, borrowers may also qualify for income-driven repayment options, while some defaulted loans can be consolidated into a new Direct Consolidation Loan under qualifying conditions. With involuntary collections currently delayed, borrowers who are concerned about future offsets have a window to contact their loan holder or the Education Department's Default Resolution Group (DRG) and explore their options.
Bottom line
Could losing even $100 or $200 from your monthly Social Security benefit disrupt your retirement budget? If so, checking the status of any old federal student loans now makes sense, particularly because the current pause on involuntary collections isn't the same thing as permanent protection.
Getting a defaulted loan back into good standing could remove a risk that becomes much harder to manage once Social Security is a major part of your monthly income.
There's also time to respond before an offset suddenly appears. Federal Student Aid says borrowers facing a Treasury offset receive written notification before federal benefit payments are scheduled to be withheld, giving them an opportunity to address the debt.
Knowing your loan status, your repayment options, and how much income you could potentially lose can help eliminate some stress living on Social Security and make your retirement budget more predictable.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.


- Huge discounts on travel, groceries, prescriptions and more
- Access to financial planning resources and health tools
- Join AARP and get 25% off with automatic renewal




