






 Add Us On Google

According to data from Fidelity, the average 401(k) balance of Americans between ages 65 and 69 is $258,800. Data from Empower reports a higher 401(k) balance of $579,957 for someone in their 60s, but the median is $190,151.
If you feel behind on your retirement savings and you want to get ahead financially, here are a few tips.
Now Available: The Definitive Guide to Retirement Income
Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.
That is exactly what The Definitive Guide to Retirement Income helps answer.1 <p class="">Investing in securities involves a risk of loss. Past performance is never a guarantee of future returns. Investing in foreign stock markets involves additional risks, such as the risk of currency fluctuations. Guides are provided by Fisher Investments. The publisher may be compensated when readers request a guide.</p> It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›
The median 401(k) balance for workers 65 to 69
The median 401(k) balance that Empower reports is a more accurate reflection of what a typical retiree in their 60s likely has. That's because a smaller group of high earners who contribute significantly to their 401(k)s tend to bring up the average.
The median shows that about half of retirees have above that number saved in a retirement account, and half have below. Because of that, it's a good guideline for those in their 60s to see how they compare to their peers.
The 401(k) benchmark that experts recommend
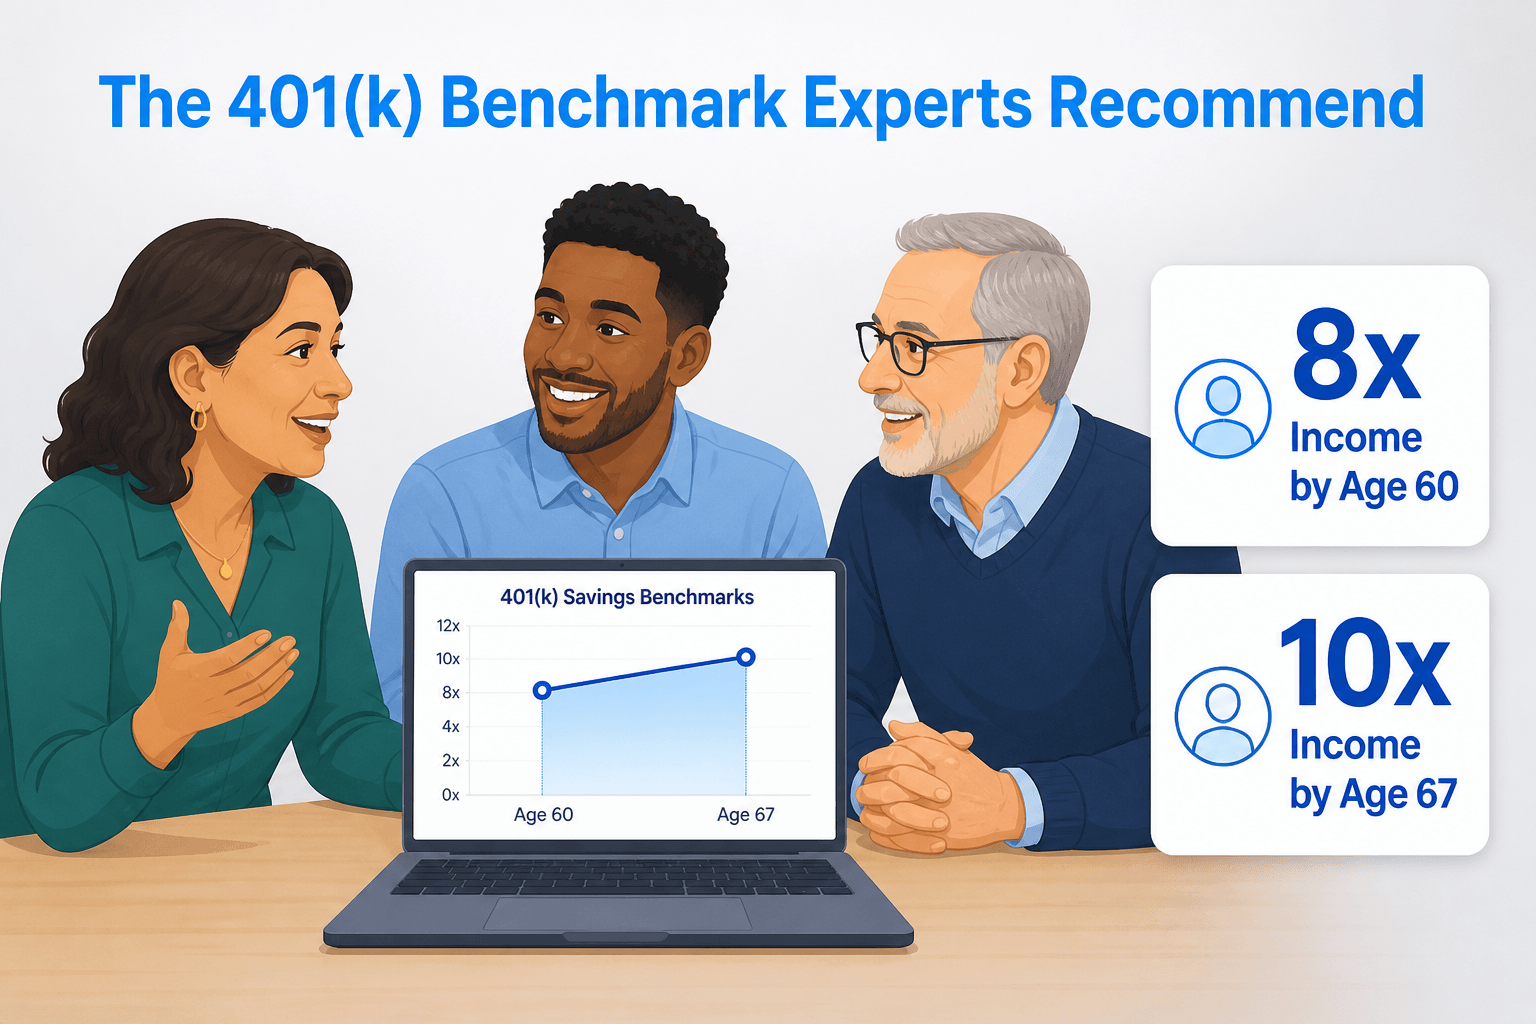
If you're not sure what retirement benchmark you should reach before leaving work, Fidelity provides guidelines. According to their data, workers should aim to have eight times their income saved by 60 and ten times their income saved by 67. This is not a retirement rule; it's more of a benchmark to consider if you want to retire comfortably.
Balances tend to dip in your 60s as you retire and start taking withdrawals
When you're in your 60s, many people leave the workforce and start making withdrawals from their 401(k)s. Though workers could start receiving Social Security checks at age 62, many people wait until the full retirement age of 67 to avoid receiving reduced benefits.
The best timing for receiving Social Security benefits could be different for everyone, and consulting with a financial advisor could help you determine the best path for you.
Released: The Definitive Guide to Retirement Income (Sponsor)
Most people spend their entire working lives focusing on one thing: growing a pile of money. Then they retire and discover the skill they actually need is close to the opposite. Turning that pile into steady income, year after year, through good markets and bad, without ever running out. It may be the least discussed and most consequential transition in personal finance, and plenty of otherwise careful investors walk into it with no real plan.
That is exactly what The Definitive Guide to Retirement Income helps answer.1 <p class="">Investing in securities involves a risk of loss. Past performance is never a guarantee of future returns. Investing in foreign stock markets involves additional risks, such as the risk of currency fluctuations. Guides are provided by Fisher Investments. The publisher may be compensated when readers request a guide.</p> It is a free guide from Fisher Investments covering what your retirement will really cost, where the cash flow should come from, and how much you can safely withdraw each year. Learn More Here ›
A 401(k) balance is only one piece of the retirement puzzle
Many people focus on 401(k) balances, but your retirement account is only one piece of your total net worth. Your net worth is your assets minus your liabilities. Assets include your retirement plan, real estate, pensions, and other savings.
Retirees could leverage these assets to create income streams. So, even if you feel behind when it comes to your 401(k) balance, you may have other retirement income streams like a pension and Social Security checks.
Your financial habits are just as important as your retirement balance
In many ways, your financial habits are just as important as, if not more important than, your retirement balance. Someone with a very high 401(k) balance may use it quickly if they have high spending habits.
On the other hand, someone with a 401(k) balance closer to the median may be able to stretch it to last for many decades because of their frugal spending habits. Where you live also impacts your retirement costs, as some states have particularly high housing costs.
Find out how much income you need in retirement
If you're considering retiring soon and you're not sure about next steps, first find out how much income you need in retirement. Understanding how much cash flow you need to cover your wants and needs during your golden years could be useful.
Once you have that number, you could look at your assets to see whether you'll be able to support yourself after you stop working.
If you're facing a retirement gap, you could take advantage of "Super Catch-Up" contributions once you turn 60. This allows workers aged 60 to 63 to contribute an extra $11,250 in addition to the $24,500 401(k) maximum. Super catch-up contributions are the last major opportunity to top off your 401(k) before retirement.
Retirement News: Almost 80% of Americans fear a retirement age increase — here’s the real reason why
Consult with a financial advisor if you need help making a retirement plan
If you're not sure whether or not you're on the right track with your finances, make an appointment with a financial planner. They could review your assets, retirement plan, and your full financial picture and help you determine whether or not you'll be able to retire in the near future.
A financial advisor could also recommend the best withdrawal strategy for you once you do retire, which could help you optimize your taxes so you don't get an unexpected tax surprise once you stop working.
Bottom line
Once you're retired, you might not want to worry about earning extra money. If that's the case, preparing for retirement becomes more important. If you feel behind or have less than the average saved in a 401(k), remember that retirement accounts are only part of your financial picture, and a financial advisor could help you determine the best next steps for you.
More from FinanceBuzz:
- 12 ways to pocket up to $300.
- Are you a homeowner? Get a protection plan on all your appliances.
- 10 little weird hacks Costco shoppers should know.
- Learn how to escape the paycheck-to-paycheck grind.


- Huge discounts on travel, groceries, prescriptions and more
- Access to financial planning resources and health tools
- Join AARP and get 25% off with automatic renewal






