





 Add Us On Google

At 80, you're long past the years when building retirement savings was a priority. They're something you're living on, so what's relevant for you has changed from how much you could still put away to how far what's left could actually go.
Knowing where you stand compared to other households your age is a useful gut check. Still, by 80, your readiness depends on your full income picture rather than on any single account balance.
That's not to say the comparison isn't worth making, if only to find out whether what you have, combined with everything else coming in, could cover all the expenses in your retirement plan. There's only one way to find out.
Get a protection plan on all your appliances
Did you know if your air conditioner stops working, your homeowner’s insurance won’t cover it? Same with plumbing, electrical issues, appliances, and more.
A home warranty from Choice Home Warranty could pick up the slack where insurance falls short.
For a limited time, you can get your first month free with a Single Payment home warranty plan.
How much does the typical 80-year-old have left in retirement savings?
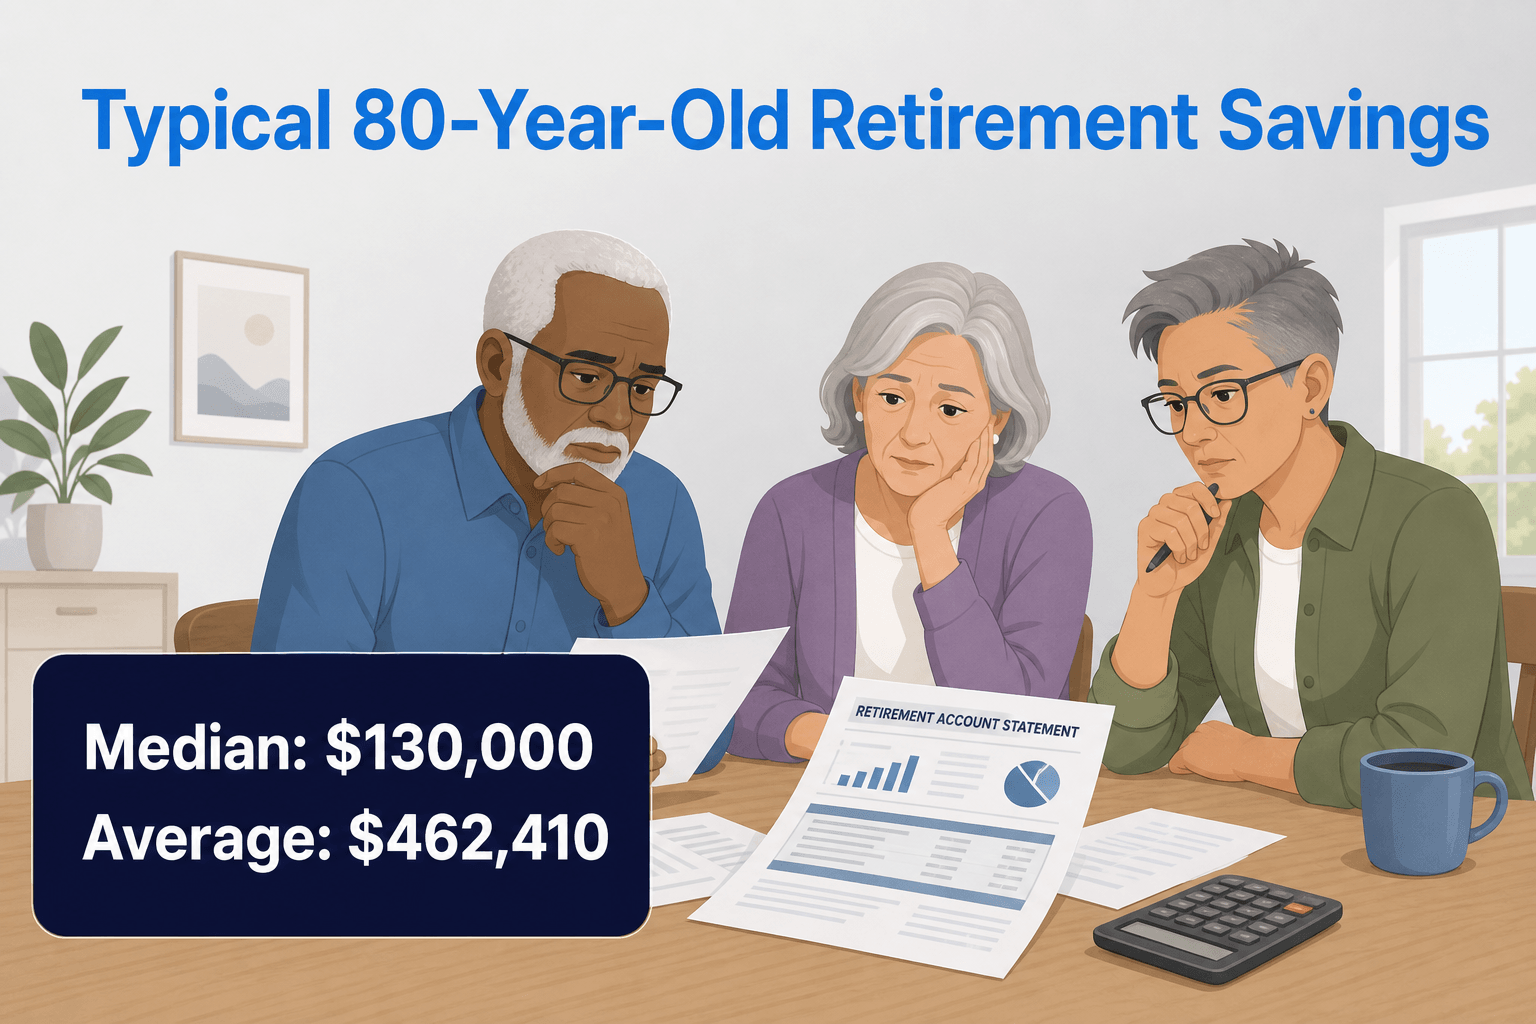
The Federal Reserve doesn't have an exact figure for age 80. The latest Survey of Consumer Finances groups households aged 75 and older together. Retirees in that age range with a retirement account have a median balance of $130,000, while the average is $462,410.
This benchmark is one of the few where the median matters more than the average because it paints a more realistic picture of what a typical 80-year-old household has left than the average figure suggests.
Why the average sits so far above the median
At $462,410, the average balance for households 75 and older is more than three times the $130,000 median. The gap is easy to explain. By definition, averages get a boost from the relatively small number of retirees with very large accounts.
By contrast, the median shows the midpoint. On one side, half of 80-year-olds have more than $130,000. On the other, half of them have less than that. Using this stand-in for a typical household is better than using the average, which may make even a reasonable balance look inadequate by comparison.
Still, remember that even $130,000 isn't your target. It does little more than mark the middle of a wide range.
Why the number looks smaller than it used to
For many people, this balance shows the opposite of what it did at the beginning of retirement. Instead of years of contributions, it reflects years of withdrawals. Add in market volatility, required minimum distributions, and the everyday cost of covering expenses without a monthly paycheck, and a balance that looked impressive when you retired may look much thinner 15 or 20 years later. That's just normal, and no cause for alarm.
By 80, retirement savings are usually just one piece of your income, alongside Social Security, a pension, and, for many seniors, home equity. half of 80-year-olds have more than $130,000. For most, Social Security and other income sources are doing the bulk of the work.
If you’re over 50, take advantage of massive discounts and financial resources
Over 50? Join AARP today— because if you’re not a member you could be missing out on huge perks. When you start your membership today, you can get discounts on things like travel, meal deliveries, eyeglasses, prescriptions that aren’t covered by insurance and more.
Start your membership by creating an account here and filling in all of the information (Do not skip this step!) Doing so will allow you to take up to 25% off your AARP membership, making it just $15 the first year with auto-renewal.
Don't let the national number fool you
Comparing yourself with the benchmark is useful, as long as you understand that the number doesn't mean the same thing for everyone.
If two 80-year-olds have the same $130,000 balance, it doesn't mean their financial pictures are identical. One may live in a paid-off home, collect a pension alongside benefits, and spend conservatively. The other may be renting, have no pension, and draw down savings faster than planned to keep up with rising costs.
Their identical balances don't tell you much about who's actually in better shape.
What if your balance is well below the benchmark?
If your remaining savings are modest, it's not the end of the world.
To understand your situation, you should add up all income sources, not just savings. Social Security, pensions, home equity, and annuity income all count toward what you have to spend each month. Also, revisit your withdrawal rate. If the account is smaller than planned, you should slow down the pace.
Even so, your budget may still not be enough. One alternative is home equity. Downsizing or a reverse mortgage could change the math without touching remaining savings.
Whatever you do, protect your spouse. Household income typically drops when one spouse dies because only the higher of the two Social Security incomes continues rather than both. Talk through any income needs and survivor-benefit decisions in advance.
Turn the benchmark into a real check-up
Measuring yourself against $130,000 may be tempting. However, it's more useful to find out whether your total income, savings withdrawals, Social Security, pension, and any home equity you could tap could cover what you actually spend each month, with some room for the unexpected.
A modest balance paired with low fixed expenses and steady Social Security may be perfectly sustainable. A larger balance paired with high costs and no other income could still fall short.
Retirement News: Almost 80% of Americans fear a retirement age increase — here’s the real reason why
Bottom line
Using a savings benchmark could be eye-opening, but it may not tell you whether you have enough money. At 80, households with a dedicated retirement account hold a median amount of $130,000. This isn't a verdict on your financial fitness. Your spending habits, income sources, and whether your spouse depends on that income matter more than where you land next to a national number.
Want a tip? To review your finances, use the number as the prompt. Add up your total income, compare it with what you're actually spending, and make sure your spouse is protected if something happens to you. That's a more useful exercise than chasing the perfect balance.
FAQs
How can I help protect my spouse financially?
Review Social Security survivor benefits, pension survivor options, beneficiary designations, and how household expenses would be covered after one spouse dies. Because one Social Security payment generally ends, couples should plan for how the surviving spouse would manage on a lower monthly income.
Why is the average retirement balance so much higher than the median?
A relatively small number of households with substantial retirement savings pull the average higher. The median represents the midpoint, meaning half of households have more and half have less, so it may provide a more realistic comparison for a typical retiree.
What matters more than retirement savings at age 80?
Your total financial picture matters more than any single account balance. Consider your monthly income, housing costs, health care expenses, debt, withdrawal rate, home equity, and whether a spouse depends on your income.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.


- Huge discounts on travel, groceries, prescriptions and more
- Access to financial planning resources and health tools
- Join AARP and get 25% off with automatic renewal