








 Add Us On Google

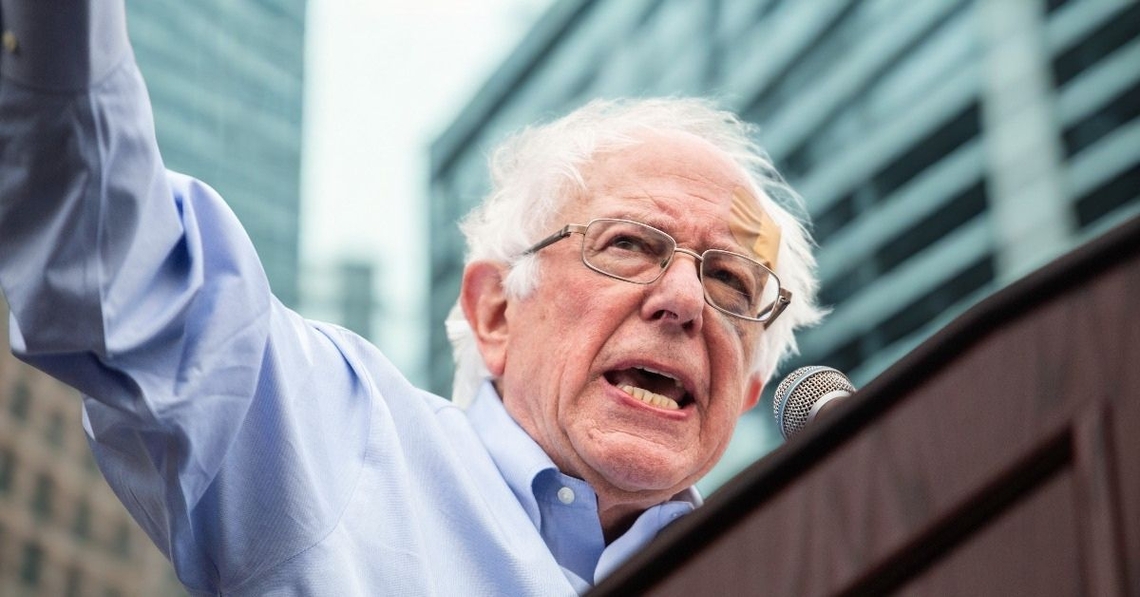
Social Security changes could move through Congress much faster under a new bipartisan proposal, and Bernie Sanders wants Democrats to put the brakes on it.
In an early August letter to every Democratic senator, he called the fast-track approach "absurd, anti-democratic and unacceptable." The Vermont senator worries that a shorter timeline could leave retirees with less time to understand changes that may eventually reach their senior benefits.
Here's why he's pushing back and what retirees should know as the proposal moves forward.
Now Available: The Definitive Guide to Retirement Income
Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.
That is exactly what The Definitive Guide to Retirement Income helps answer.1 <p class="">Investing in securities involves a risk of loss. Past performance is never a guarantee of future returns. Investing in foreign stock markets involves additional risks, such as the risk of currency fluctuations. Guides are provided by Fisher Investments. The publisher may be compensated when readers request a guide.</p> It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›
The warning Sanders sent to Senate Democrats
Sanders made his position clear in an August 3 letter to fellow Democrats with the subject line, "Oppose Fast-Tracking Social Security Cuts in the Lame Duck." He urged them to reject legislation that "fast-tracks fundamental changes to Social Security through an unelected commission," arguing that the process could make it easier to reduce benefits while limiting public debate.
Two days later, Sanders told the Senate Finance Committee what he would rather have Congress do. "The bottom line here is... we've got to do what senior advocates for years have said, lift that cap," he said, referring to the $184,500 limit on wages subject to Social Security payroll tax.
The part of the PROMISE Act raising concerns
Sanders' warning is aimed at the PROMISE Act, a bipartisan bill introduced in July that would put Social Security changes on a faster track through Congress.
Under the proposal, the Social Security Advisory Board would come up with a plan to address the program's finances, then Congress would face tighter deadlines to act. Debate would be limited, and lawmakers would have less room to change the proposal once it reaches the floor.
Sanders worries that a process like that could make it easier to move changes such as benefit cuts or a higher retirement age before the public has had much time to weigh in.
The bill's sponsors, on the other hand, believe those deadlines are exactly what Congress needs. With Social Security's funding deadline getting closer, they argue that a faster process could keep lawmakers from putting off a solution yet again.
How Sanders wants to shore up Social Security
Sanders wants Congress to bring more money into Social Security by asking higher earners to pay more. Right now, the payroll tax only applies to the first $184,500 in wages, so someone earning $500,000 stops paying Social Security tax at the same point as someone earning $184,500.
Removing that cap would raise taxes for roughly the top 6% of earners without increasing the bill for workers below it.
His Social Security Expansion Act would also collect more from certain investment income above $250,000, with some of that money going toward a roughly $200 monthly benefit increase.
Instead of speeding up the process and filling in the details later, Sanders wants Congress to debate the tax increases and benefit boost up front. How much that would extend Social Security's finances would depend on the final version lawmakers agree on.
Released: The Definitive Guide to Retirement Income (Sponsor)
Most people spend their entire working lives focusing on one thing: growing a pile of money. Then they retire and discover the skill they actually need is close to the opposite. Turning that pile into steady income, year after year, through good markets and bad, without ever running out. It may be the least discussed and most consequential transition in personal finance, and plenty of otherwise careful investors walk into it with no real plan.
That is exactly what The Definitive Guide to Retirement Income helps answer.1 <p class="">Investing in securities involves a risk of loss. Past performance is never a guarantee of future returns. Investing in foreign stock markets involves additional risks, such as the risk of currency fluctuations. Guides are provided by Fisher Investments. The publisher may be compensated when readers request a guide.</p> It is a free guide from Fisher Investments covering what your retirement will really cost, where the cash flow should come from, and how much you can safely withdraw each year. Learn More Here ›
Why the PROMISE Act could face a tougher Senate path
Sanders sent his warning to every Democratic senator, putting concerns about possible benefit cuts directly in front of lawmakers who may be considering the PROMISE Act. AARP, the country's largest retiree advocacy group, has raised similar concerns about the process and argues that Social Security changes deserve full public debate through the regular legislative process.
With both Sanders and AARP pushing back, some Democrats may be less comfortable supporting the bill despite its bipartisan backing. If enough of them hold off, supporters could have a much harder time finding the votes to move it forward.
What happens if Congress waits too long
Social Security's retirement trust fund is projected to run out in late 2032. If Congress reaches that point without a fix, the program would only be able to pay about 78% of scheduled benefits.
For a retiree expecting a $2,000 monthly check, that would mean roughly $1,560 instead. The cut would happen automatically because Social Security wouldn't have enough money coming in to cover the full amount.
That possibility hangs over both sides of the debate. The longer lawmakers spend disagreeing over how to fix Social Security, the less time they have to reach a deal before the funding deadline arrives.
How close this debate is to affecting your check
Neither Sanders' letter nor the PROMISE Act would change your Social Security check on its own. Any changes to benefits or taxes would come later, based on the funding plan Congress eventually considers.
His preferred approach would bring more money into Social Security without reducing benefits, while the PROMISE Act would create a process that could produce any combination of fixes. How Democrats respond to the bill in the coming months could give retirees a better idea of which direction Congress may be heading.
Retirement News: Almost 80% of Americans fear a retirement age increase — here’s the real reason why
Bottom line
Social Security has been waiting on a long-term fix for years, and the PROMISE Act is another attempt to get Congress moving. Sanders' warning is that moving too quickly could come with its own cost if retirees don't get enough time to understand what's being considered.
None of this means you need to rethink your retirement plan today. What's worth watching is whether Congress could finally find a solution retirees could live with, without rushing changes that could follow them for years. Until that happens, the debate is far from settled.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.


- Huge discounts on travel, groceries, prescriptions and more
- Access to financial planning resources and health tools
- Join AARP and get 25% off with automatic renewal






