





 Add Us On Google

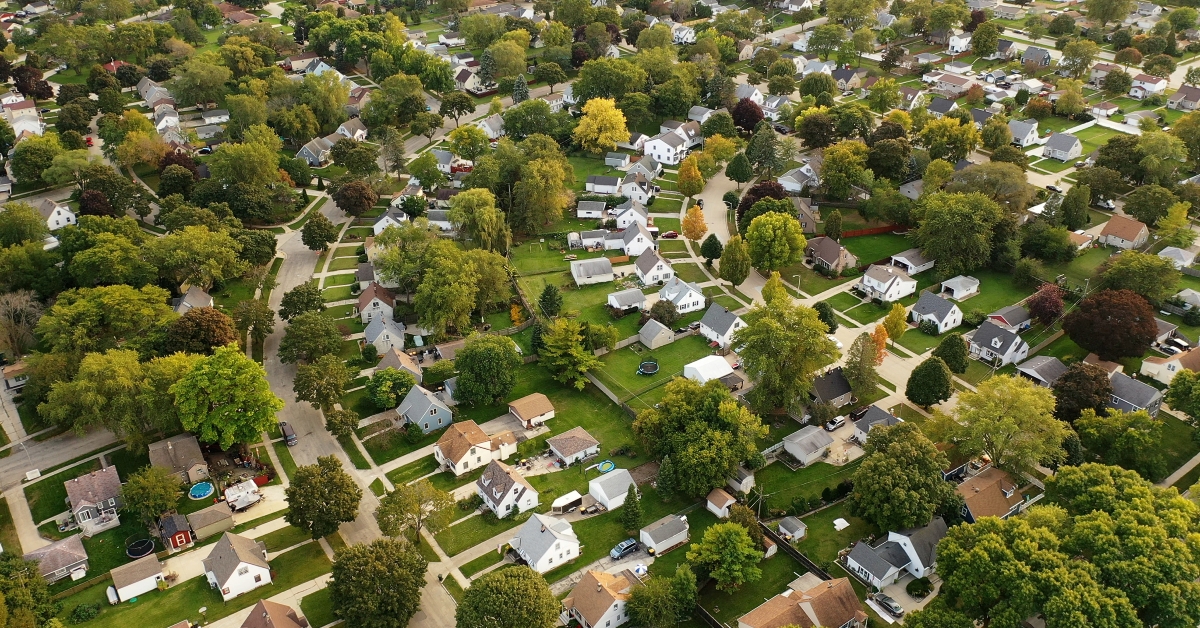
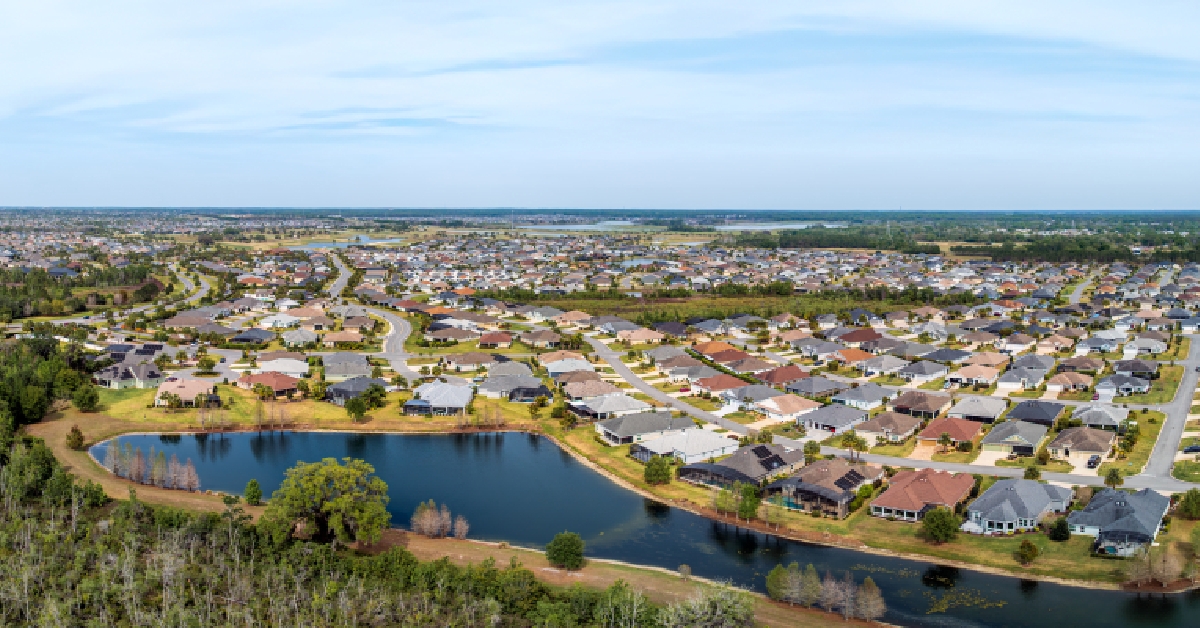
Two homes in The Villages may look identical, sit just a few streets apart, and still come with very different property tax bills.
The Villages isn't entirely in one county. It stretches across three counties, and some homes also fall within city limits, which adds another layer of property taxes. These costs may substantially affect your retirement plan because you pay them every year, so a small difference on a listing could add up to thousands of dollars.
If you're shopping for a home in The Villages, the listing price is less important than the exact address, right down to the taxing district.
Get a protection plan on all your appliances
Did you know if your air conditioner stops working, your homeowner’s insurance won’t cover it? Same with plumbing, electrical issues, appliances, and more.
A home warranty from Choice Home Warranty could pick up the slack where insurance falls short.
For a limited time, you can get your first month free with a Single Payment home warranty plan.
The county line changes your tax bill
The Villages straddles three Florida counties: Sumter, Lake, and Marion. Each county sets its millage rate, or the amount charged per $1,000 of taxable value. The rates are far from identical.
In 2025, a home in unincorporated Sumter County carried a total millage of 10.03 mills, compared to 13.45 mills in Lake County and 15.62 mills in Marion County, according to Scout The Villages.
That doesn't mean a $400,000 home in Sumter automatically generates a $4,000 tax bill. Florida's taxes are based on taxable value, not simply the home's purchase price. Exemptions and assessments also affect the final bill.
Two similarly priced homes may have very different annual costs because of the different rates.
City limits add another layer
The county isn't always the only thing that affects taxes. Some homes in southern Sumter County fall within the City of Wildwood. The city adds its own millage rate to the county taxes, bringing the total to roughly 12.86 mills in the example above.
In the Lake County portion, homes within Lady Lake of Fruitland Park also have municipal taxes added to their bills.
In other words, buying "in The Villages" doesn't tell you what you pay in taxes. You need to know exactly where that particular property sits.
The county line isn't obvious from the street
The Villages is laid out as one giant community. However, its county and municipal boundaries don't always match what you see on the ground. A golf-cart ride could take you from one taxing jurisdiction to another without any obvious change in the homes, landscaping, or amenities around you.
The difference doesn't jump out at you in a listing, either, so don't rely on the ZIP code to estimate your future property taxes.
If you’re over 50, take advantage of massive discounts and financial resources
Over 50? Join AARP today— because if you’re not a member you could be missing out on huge perks. When you start your membership today, you can get discounts on things like travel, meal deliveries, eyeglasses, prescriptions that aren’t covered by insurance and more.
Start your membership by creating an account here and filling in all of the information (Do not skip this step!) Doing so will allow you to take up to 25% off your AARP membership, making it just $15 the first year with auto-renewal.
Why the gap exists
There's a simple reason the rates don't all match: not all local governments fund their services the same way. Some costs are included in a county's general tax rate. Others are collected through separate taxing districts or municipal levies.
Those differences aren't visible to a home shopper, but they're built into each property's tax bill. You don't need to understand every taxing district to avoid the problem, but remember that the address determines which ones apply.
Don't assume the seller's tax bill is your future bill
The seller's current property tax bill doesn't necessarily become yours after buying the house. Florida's homestead exemption and Save Our Homes assessment protections may keep a longtime homeowner's taxable value below the home's current market value.
After a sale, the property's assessed value could change, so using the seller's bill as your estimate is misleading. If you're buying the property as your primary residence, only factor in the homestead exemption you're eligible to receive.
Check the exact property before making an offer
The best way to compare two Villages homes is to look up each specific property.
The county property appraiser records help you confirm:
- The county the home is in
- Whether it's inside city limits
- The taxing district(s) that apply
- Current assessed and taxable values
- A homestead exemption
Before making an offer, check with the relevant county property appraiser for properties in Sumter, Marion, or Lake County. Don't wait until after you've already fallen in love with the house.
Retirement News: Almost 80% of Americans fear a retirement age increase — here’s the real reason why
Check for a CDD bond, too
Property taxes aren't the only recurring cost that may differ in The Villages.
Some homes have a Community Development District, or CDD, bond assessment used to repay infrastructure costs. CDD maintenance assessments may also appear separately on the tax bill.
These aren't part of the millage rate, and the Save Our Homes assessment cap doesn't cover them.
As a result, a newer home could have a substantially different total annual bill than an older resale home nearby, even at identical prices.
Compare what you'll pay every year
The listing price doesn't tell you the full annual cost of your home, including:
- Property taxes
- City taxes
- CDD bond and maintenance assessments
- Other special assessments
- Expected assessed value and exemptions
For example, a $10,000 difference in purchase price may look significant until you discover that the less expensive home has substantially higher recurring costs. The point is to know what you're actually buying, rather than automatically choosing one county over another.
Verify the numbers before you close
Property tax rates change from year to year, so an old article, online calculator, or listing estimate isn't reliable for your final number. Before closing, verify current rates and assessments with the county property appraiser and review the property's most recent tax bill.
Unlike the house, property taxes aren't a one-time expense, so it's worth checking the county line and the exact taxing district on the other side of it before you sign the paperwork.
Get instant access to hundreds of discounts
Over 50? Join AARP today— because if you’re not a member you could be missing out on huge perks like discounts on travel, dining, and even prescriptions.
Get 25% off membership — just $15 for your first year with auto-renewal — and a free gift if you join today.
Bottom line
The Villages may look like one community on a map, but your property tax bill depends on exactly where your home is located. Two similar homes may have different annual costs because they're in different counties, different cities, or different taxing districts.
To keep more of your money, look up the exact address, check its current tax and assessment records, find out whether a CDD bond remains, and estimate what your yearly bill could look like. A home that looks like the best deal on the listing page isn't always the cheapest home to own.
More from FinanceBuzz:
- 12 ways to pocket up to $300.
- Are you a homeowner? Get a protection plan on all your appliances.
- 10 little weird hacks Costco shoppers should know.
- Learn how to escape the paycheck-to-paycheck grind.


- Huge discounts on travel, groceries, prescriptions and more
- Access to financial planning resources and health tools
- Join AARP and get 25% off with automatic renewal