Add Us On Google

If you're building a retirement plan to see you well into your 80s or 90s, you probably wonder just how much money you'll need at that point. One metric to consider is how much others at that age have saved up — specifically, what an 80-year-old's bank account balance would be.
While the Federal Reserve has data for broader age brackets, and not specifically 80, you can use this information to see where you stand financially. Just take it with a grain of salt. Financial health is often more than a number.
Set up direct deposit - pocket $400
Set up an eligible direct deposit with SoFi Checking and Savings and you could pocket a bonus of up to $400. Make the switch, set up direct deposit, earn the bonus. It basically takes no extra work at all other than following these steps.
Why people are switching: This account earns up to an insane 4.00% APY1 <p>Earn up to 4.00% Annual Percentage Yield (APY) on one SoFi Savings account with a 0.90% APY Boost (added to the 3.10% APY as of 5/28/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/26. Rates are variable, subject to change. Terms apply at <a href="https://www.sofi.com/banking/#4">sofi.com/banking#4</a>. SoFi Bank, N.A. Member FDIC.</p> on savings for up to six months (3.10% APY standard + 0.90% APY boost) on top of that $50 or $400 bonus.2 <p>New and existing Checking and Savings members who have not previously enrolled in Direct Deposit with SoFi are eligible to earn a cash bonus of either $50 (with at least $1,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more) OR $400 (with at least $5,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more). Cash bonus amount will be based on the total amount of Eligible Direct Deposit received within 25 calendar days of your first Eligible Direct Deposit of $1 or more. If you have satisfied the Eligible Direct Deposit requirements but have not received a cash bonus in your Checking account, please contact us at 855-456-7634 with the details of your Eligible Direct Deposit. Direct Deposit Promotion begins on 5/15/2026 and will be available through 12/31/26. See full bonus and annual percentage yield (APY) terms at <a href="https://www.sofi.com/banking/checking-offer/">sofi.com/banking/checking-offer/</a></p> That's way better than the measly 0.38% APY (as of 06/15/26)3 <p>Based on <a href="https://www.fdic.gov/national-rates-and-rate-caps">this</a> FDIC data, as of 6/15/26.</p> national average savings accounts offer.
No monthly fees and no surprises. Open your account and earn up to a $400 bonus
The typical bank account balance for an 80-year-old
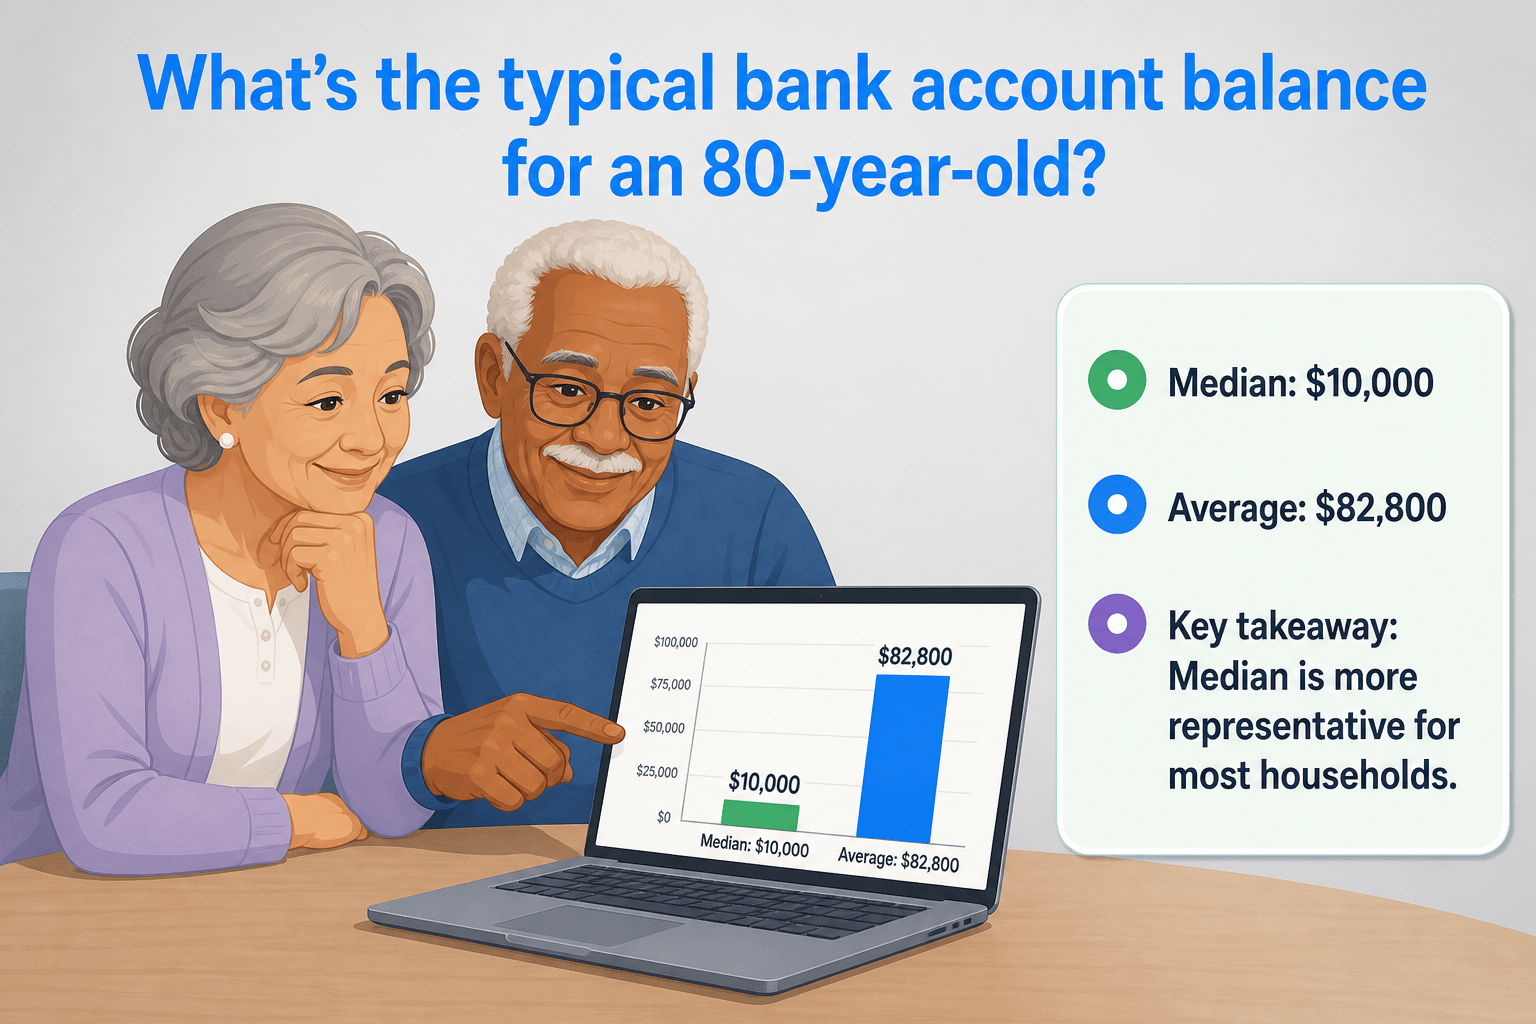
Federal Reserve data show that households whose reference person was age 75 or older had a median of around $10,000 in readily accessible transaction accounts. The average, calculated as the total balances held by households in the group divided by the number of households with transaction accounts, was much higher, at about $82,800.
The figures don't specifically share data for someone aged 80, but you can assume that the bracket of 75+ isn't far off from what an older retiree might have.
The bigger gap isn't in age, it's in average vs. median, with median a more likely number for the average American to compare to. It looks at the bank account balance in the middle of the pack, with half of the accounts having higher balances and half having lower. Unlike the average, it's not skewed as much by unusually high balances.
Which accounts are included in the data?
The Federal Reserve data specifically calls out transaction accounts, which are accounts where the money is easily accessible. They include:
- Checking and savings accounts
- Money market deposit accounts and money market funds
- Call accounts
- Prepaid debit cards
The data doesn't include 401(k)s, 403(b)s, traditional or Roth IRAs, pensions, stocks, mutual funds, bonds, home equity, real estate, or total net worth. Certificates of deposit may be FDIC-insured bank deposits, but they are not included in the Federal Reserve's transaction-account category used for these figures.
Why bank account balances don't tell the whole story
Because the data only includes some types of accounts, and not others, it's not a measurement of wealth or financial stability. Someone could have a paid-off home and a large IRA but keep very little cash in a savings or checking account.
Likewise, you could keep most everything you own in a money market account and have significant high-interest debt and no retirement accounts or pension. The bank account figures are a useful metric, but they can't be relied upon alone to know if you're "on track" for your age.
Resolve $10,000 or more of your debt
National Debt Relief could help you resolve your credit card debt with an affordable plan that works for you. Just tell them your situation, then find out your debt relief options.4 <p>Please note that all calls with the company may be recorded or monitored for quality assurance and training purposes. Clients who are able to stay with the program and get all their debt settled realize approximate savings of 45% before fees, or 20% including our fees, over 24 to 48 months. All claims are based on enrolled debts. Not all debts are eligible for enrollment. Not all clients complete our program for various reasons, including their ability to save sufficient funds. Estimates based on prior results, which will vary based on specific circumstances. We do not guarantee that your debts will be lowered by a specific amount or percentage or that you will be debt-free within a specific period of time. We do not assume consumer debt, make monthly payments to creditors or provide tax, bankruptcy, accounting or legal advice or credit repair services. Not available in all states. Please contact a tax professional to discuss tax consequences of settlement. Please consult with a bankruptcy attorney for more information on bankruptcy. Depending on your state, we may be available to recommend a local tax professional and/or bankruptcy attorney. Read and understand all program materials prior to enrollment, including potential adverse impact on credit rating. "Debt-Free" applies only to enrolled credit cards, personal loans, and medical bills. Not mortgages, car loans, or other debts. Results vary.</p>
Sign up for a free debt assessment here.
Can less cash in retirement be a good thing?
There's another angle to consider, and it's that it may be better if you don't have as much in the bank. Lower liquid cash balances at this stage of life can be reasonable if you have enough coming in from Social Security, pensions, annuities, required distributions, or withdrawals from other retirement accounts. Some may even have income from a rental property or business at age 80.
If you have a paid-off home or land, this asset value is in something steady and predictable, even if it's not as liquid. If you're able to make your monthly bills, have a healthy cash cushion, and don't scramble to pay for unexpected health expenses, the modest cash balance can be fine.
Depending on the account and investment chosen, money held outside a low-yield transaction account may have greater long-term return potential, but it can also involve market risk, loss of principal, or reduced access to cash.
The national number isn't a rule
Instead of comparing yourself to aggregate data from households not in your geographic area or with the same lifestyle values, consider what you need to be "well off." Calculate the number of months your liquid cash could cover, if needed. Factor in housing, property taxes, insurance, utilities, food, medical bills, transportation, and repairs.
For example, a retiree with $24,000 in the bank and $3,000 in essential monthly expenses has around 8 months of basic needs covered. But someone with that same amount and $6,000 in monthly expenses would only have 4 months covered. There's a big difference in financial stability with the same bank account balance at play.
When more cash makes sense
Having a higher liquid balance may be beneficial for those with higher out-of-pocket medical expenses, a large insurance deductible, or long-term care expenses not covered by insurance. It may be a wise move for those with irregular, unpredictable monthly income.
Those with substantial debt payments or who need cash to avoid selling investments after a market decline should consider more of a cash cushion as well. You may consider two buckets: one for regular bills and one for unexpected expenses, to make sure you have enough on hand for what you need and don't have to sell assets if something goes wrong.
Bottom line
The $10,000 median transaction account balance is for an entire household with a reporting 75+ member, not just a single earner, and it's much lower than the national average of $82,800 for this age group. But these numbers have less meaning than your own budget and income realities.
If you do need to open a new bank account, be sure it's held in an FDIC-insured bank so it's protected. It generally covers deposits up to $250,000 per depositor for each ownership category.
FAQs
Can having less cash in the bank be reasonable during retirement?
Yes. A lower balance may be adequate if reliable income from Social Security, pensions, annuities, retirement-account withdrawals, rental property, or a business covers your expenses. Owning a paid-off home can also strengthen your finances, although home equity is not readily accessible cash.
Why is the average bank balance so much higher than the median?
A relatively small number of households with very large balances can push the average upward. The median represents the middle household, half have more and half have less, so it may offer a more useful comparison for many retirees.
How should retirees organize their available cash?
One option is to maintain two cash buckets: one for regular living expenses and another for emergencies. This can make routine bills easier to manage while providing funds for unexpected medical costs, repairs, or other urgent needs.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.


Intro Offer
INTRO OFFER: Unlimited Cashback Match for all new cardmembers. Discover will automatically match all the cash back you’ve earned at the end of your first year! There’s no minimum spending or maximum rewards. You could turn $150 cash back into $300
Annual Fee $0 Why we like it