





 Add Us On Google

Let's say two homeowners have the same loan terms: a 30-year fixed-rate mortgage at 6.59%. The difference? One lives in Honolulu and the other in Pensacola, Florida.
A study of nearly 450 metro areas by Neighbors Bank shows that the Honolulu homeowner's typical principal-and-interest payment is $4,243 a month. The Pensacola homeowner's is $1,531.
While the difference may lower your financial stress if you plan to buy in Florida, the share of the total bill that goes to something other than the loan is five times larger in Pensacola.
The gap points to something many buyers learn only after closing: "fixed" describes the interest rate, not the bill.
Set up eligible direct deposit - pocket up to $400
Set up an eligible direct deposit with SoFi Checking and Savings and you could earn a bonus of $50 or $400.1 <p>New and existing Checking and Savings members who have not previously enrolled in Direct Deposit with SoFi are eligible to earn a cash bonus of either $50 (with at least $1,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more) OR $400 (with at least $5,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more). Cash bonus amount will be based on the total amount of Eligible Direct Deposit received within 25 calendar days of your first Eligible Direct Deposit of $1 or more. If you have satisfied the Eligible Direct Deposit requirements but have not received a cash bonus in your Checking account, please contact us at 855-456-7634 with the details of your Eligible Direct Deposit. Direct Deposit Promotion begins on 5/15/2026 and will be available through 12/31/2026. Full terms at <a href="https://www.sofi.com/banking/">sofi.com/banking</a>. SoFi Checking and Savings is offered through SoFi Bank, N.A., Member FDIC. SoFi members with Eligible Direct Deposit can earn 3.30% annual percentage yield (APY) on savings balances (including Vaults) and 0.50% APY on checking balances. There is no minimum Eligible Direct Deposit amount required to qualify for the 3.30% APY for savings (including Vaults). Members without Eligible Direct Deposit will earn 0.80% APY on savings balances (including Vaults) and 0.50% APY on checking balances. Interest rates are variable and subject to change at any time. These rates are current as of 9/23/26. Fees may reduce earnings. Additional information can be found at <a href="https://d32ijn7u0aqfv4.cloudfront.net/wp/wp-content/uploads/raw/SoFi-Bank-Rate-Sheet-September-23-2026.pdf">http://www.sofi.com/legal/banking-rate-sheet</a>.</p> Make the switch, set up eligible direct deposit, earn the bonus. It basically takes no extra work at all other than following these steps.
Why people are switching: This account earns up to an insane 4.40% APY2 <p>Earn up to 4.40% Annual Percentage Yield (APY) on one SoFi Savings account with a 1.10% APY Boost (added to the 3.30% APY as of 10/20/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/27. Rates are variable, subject to change. Terms apply at <a href="https://www.sofi.com/banking/#4">sofi.com/banking#4</a>. SoFi Bank, N.A. Member FDIC.</p> on savings for up to six months on new accounts (3.30% APY standard + 1.10% APY boost; terms apply) on top of that $50 or $400 bonus.1 <p>New and existing Checking and Savings members who have not previously enrolled in Direct Deposit with SoFi are eligible to earn a cash bonus of either $50 (with at least $1,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more) OR $400 (with at least $5,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more). Cash bonus amount will be based on the total amount of Eligible Direct Deposit received within 25 calendar days of your first Eligible Direct Deposit of $1 or more. If you have satisfied the Eligible Direct Deposit requirements but have not received a cash bonus in your Checking account, please contact us at 855-456-7634 with the details of your Eligible Direct Deposit. Direct Deposit Promotion begins on 5/15/2026 and will be available through 12/31/2026. Full terms at <a href="https://www.sofi.com/banking/">sofi.com/banking</a>. SoFi Checking and Savings is offered through SoFi Bank, N.A., Member FDIC. SoFi members with Eligible Direct Deposit can earn 3.30% annual percentage yield (APY) on savings balances (including Vaults) and 0.50% APY on checking balances. There is no minimum Eligible Direct Deposit amount required to qualify for the 3.30% APY for savings (including Vaults). Members without Eligible Direct Deposit will earn 0.80% APY on savings balances (including Vaults) and 0.50% APY on checking balances. Interest rates are variable and subject to change at any time. These rates are current as of 9/23/26. Fees may reduce earnings. Additional information can be found at <a href="https://d32ijn7u0aqfv4.cloudfront.net/wp/wp-content/uploads/raw/SoFi-Bank-Rate-Sheet-September-23-2026.pdf">http://www.sofi.com/legal/banking-rate-sheet</a>.</p> That's way better than the measly 0.38% APY (as of 10/19/26)3 <p>Based on <a href="https://www.fdic.gov/national-rates-and-rate-caps">this</a> FDIC data, as of 6/15/26.</p> national average savings accounts offer.
No monthly fees and no surprises. Open your account and earn up to a $400 bonus
What a fixed rate actually means
A fixed-rate mortgage removes one specific risk: your interest rate. In other words, your principal-and-interest payment stays the same for the life of the loan. If market rates jump, you're protected. If they fall, you can consider refinancing.
That's a real benefit, but it covers one line of your monthly bill.
The rest of homeownership doesn't come with a rate lock. According to The Washington Post, property taxes and homeowners insurance are two nonnegotiable costs that buyers often overlook while focusing on price and mortgage rate. Across the metro areas in the Neighbors Bank study, those two bills averaged about 21% of the monthly mortgage payment.
The parts of your bill that can move
The lender usually collects taxes and insurance through an escrow account bundled into your monthly payment. Low down-payment loans backed by the FHA, USDA, or VA typically require one, according to the above report. The lender pays your tax and insurance bills when they come due.
This is all good, but it comes with a catch. Those bills change, and your lender recalculates the escrow amount to match. When taxes and premiums go up, so does your monthly payment, even if the interest rate hasn't moved.
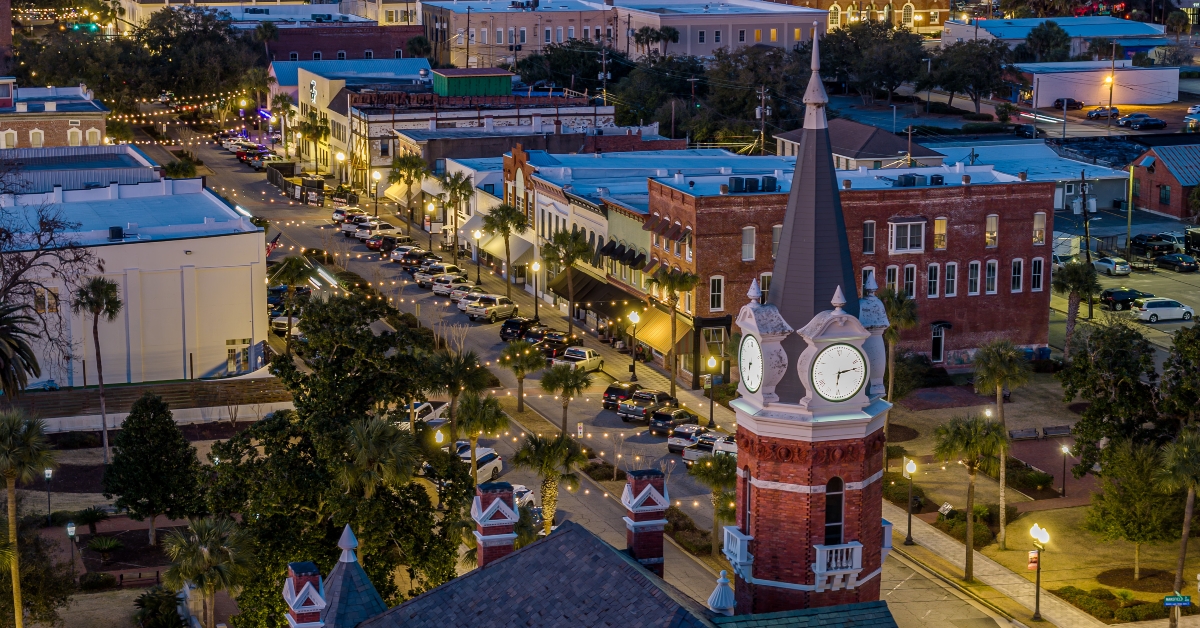
Where you live also affects your exposure. For example, Pensacola, Florida, ranked first among high-burden markets. Taxes and insurance make up 43.6% of the average payment, or $1,183 on top of $1,531 in principal and interest. At the other end of the spectrum, urban Honolulu ranked lowest at 9%, or $420 on top of $4,243.
This doesn't mean that Honolulu is better than Pensacola or vice versa. A buyer who compares only the advertised principal-and-interest payment could badly misjudge what a home will cost them each month.
Jake Vehige, president of mortgage lending at Neighbors Bank, put it plainly: "Many homeowners assume their payment will stay the same each year, but even if your mortgage rate doesn't change, taxes and insurance often do."
Some costs, like maintenance, repairs, and utilities, never show up in escrow. They're on you.
Where an adjustable-rate mortgage fits
An adjustable-rate mortgage (ARM) adds even more uncertainty. It starts with a fixed rate for an initial period. After that, the rate may adjust according to the loan's terms, and your principal-and-interest payment may change with it.
It's tempting to treat the fixed-rate loan as the safe pick and the ARM as the gamble, but that's too simple.
Both loans carry tax and insurance exposure. The fixed-rate loan removes interest-rate risk; the ARM keeps it once the initial period ends. So the real question is which risks you can absorb, and for how long.
If you plan to keep the house for decades, the adjustment terms matter a lot. If you expect to move or refinance sooner, the initial fixed period may matter more. Either way, check your loan documents for how long the initial period lasts, how often the rate may change, and how high it may go.
What to calculate before you decide how much you can afford
Before settling on a loan or a price, you should build your own number. Here's how.
Start with the full monthly payment
Add principal and interest, property taxes, homeowners insurance, and any HOA dues or mortgage insurance. This is your real monthly housing cost, not just the fixed-rate payment.
Find the actual tax and insurance numbers
Ask for the property's current tax bill and whether a sale can trigger a reassessment. Get an insurance quote for that specific address before you make an offer.
Stress-test the escrow
Maybe your taxes and insurance start at $400 a month. If they rise 5% a year, that's about $650 a month after ten years. This isn't a forecast, but it shows how a "fixed" payment drifts upward. Check whether you could handle that increase.
If you're considering an ARM, calculate the worst case
Find the maximum rate the loan allows and figure out what your payment would be at that rate. If you can't carry that payment, the loan's initial discount isn't a bargain.
Match the loan to your timeline
Decide how long you realistically expect to own the home, then ask which costs could rise during that period.
Get instant access to hundreds of discounts
Over 50? Join AARP today— because if you’re not a member you could be missing out on huge perks like discounts on travel, dining, and even prescriptions.
Get 25% off membership — just $15 for your first year with auto-renewal — and a free gift if you join today.
Budget for maintenance
It isn't in the mortgage payment, but it's part of homeownership.
Bottom line
A fixed-rate mortgage guarantees one number, but it's not your total cost of ownership. To avoid surprises and keep more of your money, you should compare loans using the home's full monthly cost and understand which expenses can rise over the years you expect to own it.
Before you make an offer, get the property's tax bill and a homeowners insurance quote, then run your budget again with both numbers a bit higher than today's. If the house still fits, you're buying with a margin of safety, not just hoping your monthly payments hold still.
This article is for informational purposes only and should not be considered investment advice.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.








- First month free
- Protection for unexpected expense
- 24/7 claims hotline
- Network of over 15,000 technicians