





 Add Us On Google

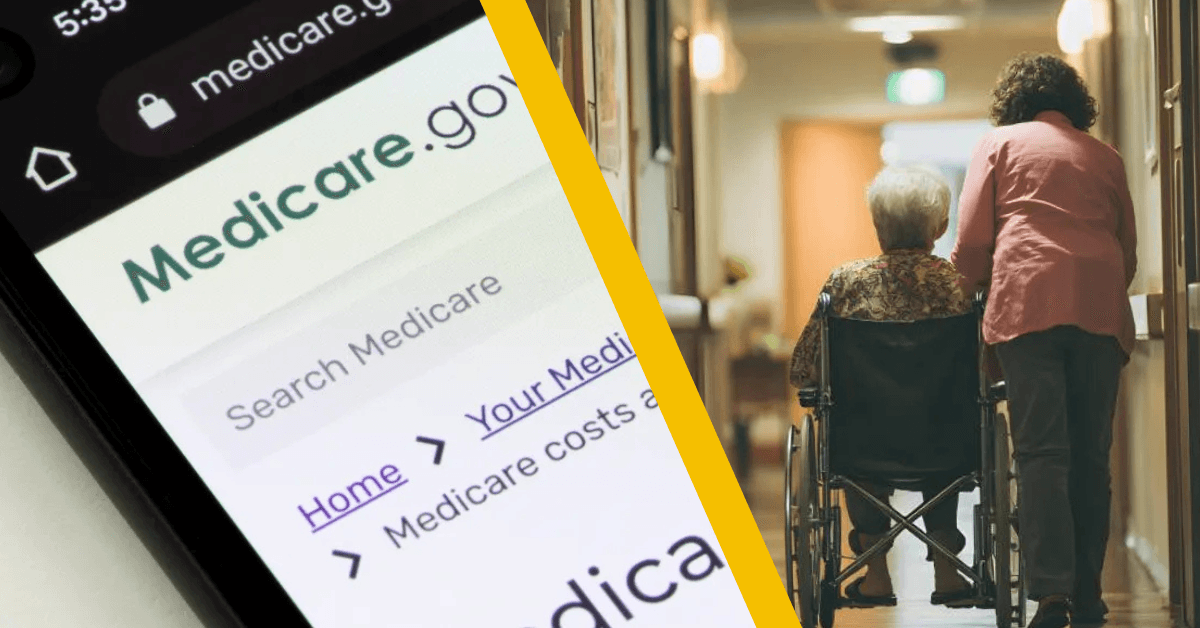
Millions of older Americans depend on Medicare to help cover medical expenses in retirement. That is why changes tied to the One Big Beautiful Bill Act (OBBBA) are drawing attention from policy experts and retirees focused on protecting their long-term financial fitness.
While President Donald Trump has repeatedly pledged to protect Medicare, several provisions in the new law could affect parts of the system over time. According to the Congressional Budget Office (CBO), the law was projected to trigger automatic Statutory Pay-As-You-Go Act (PAYGO) sequestration that could have reduced Medicare spending by roughly $45 billion in 2026 alone and about $536 billion through 2034.
However, Congress later canceled those projected Medicare cuts after resetting the statutory PAYGO scorecards. The potential sequestration did not take effect.
Here are the Medicare-related changes beneficiaries should understand.
Set up direct deposit - pocket $400
Set up an eligible direct deposit with SoFi Checking and Savings and you could pocket a bonus of up to $400. Make the switch, set up direct deposit, earn the bonus. It basically takes no extra work at all other than following these steps.
Why people are switching: This account earns up to an insane 4.00% APY1 <p>Earn up to 4.00% Annual Percentage Yield (APY) on one SoFi Savings account with a 0.90% APY Boost (added to the 3.10% APY as of 5/28/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/26. Rates are variable, subject to change. Terms apply at <a href="https://www.sofi.com/banking/#4">sofi.com/banking#4</a>. SoFi Bank, N.A. Member FDIC.</p> on savings for up to six months (3.10% APY standard + 0.90% APY boost) on top of that $50 or $400 bonus.2 <p>New and existing Checking and Savings members who have not previously enrolled in Direct Deposit with SoFi are eligible to earn a cash bonus of either $50 (with at least $1,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more) OR $400 (with at least $5,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more). Cash bonus amount will be based on the total amount of Eligible Direct Deposit received within 25 calendar days of your first Eligible Direct Deposit of $1 or more. If you have satisfied the Eligible Direct Deposit requirements but have not received a cash bonus in your Checking account, please contact us at 855-456-7634 with the details of your Eligible Direct Deposit. Direct Deposit Promotion begins on 5/15/2026 and will be available through 12/31/26. See full bonus and annual percentage yield (APY) terms at <a href="https://www.sofi.com/banking/checking-offer/">sofi.com/banking/checking-offer/</a></p> That's way better than the measly 0.38% APY (as of 06/15/26)3 <p>Based on <a href="https://www.fdic.gov/national-rates-and-rate-caps">this</a> FDIC data, as of 6/15/26.</p> national average savings accounts offer.
No monthly fees and no surprises. Open your account and earn up to a $400 bonus
Automatic Medicare spending cuts were projected for 2026
One of the biggest concerns surrounding the law involved automatic federal spending reductions tied to PAYGO budget rules. Under federal law, legislation that increases deficits can trigger mandatory spending cuts unless Congress intervenes.
The OBBBA was projected to trigger substantial Medicare sequestration cuts of as much as $45 billion in 2026 alone. These reductions would have affected payments to providers and insurers rather than directly reducing standard Medicare eligibility. However, lower reimbursement rates could potentially have affected access, plan offerings, or provider participation over time.
However, those cuts never took effect. The continuing appropriations law that reopened the federal government set the statutory PAYGO scorecards to zero for all years. As a result, no PAYGO sequestration order was required for 2026.
The roughly $45 billion and $536 billion figures therefore represent CBO projections of potential Medicare sequestration under PAYGO, not cuts beneficiaries are currently facing. A separate 2% Medicare sequestration remains in place under existing law.
Some expensive drugs may stay costly longer
The OBBBA also changes parts of Medicare's prescription drug negotiation framework. Specifically, certain orphan drugs — medications developed to treat rare diseases — may remain exempt from Medicare drug price negotiations under revised rules.
Under the new rules, drugs designated for one or more rare diseases or conditions can qualify for the orphan-drug exclusion when their only approved indications are for those rare conditions. The change applies to drug selection beginning in 2026 for negotiated prices available in 2028.
That could mean some high-cost specialty medications remain outside Medicare's price-negotiation program for longer periods. The provision changes the scope of the existing orphan-drug exclusion rather than eliminating Medicare's drug price negotiation program.
The Biden-era Inflation Reduction Act originally expanded Medicare drug price negotiation authority. The OBBBA subsequently changed the rules governing the orphan-drug exclusion.
Extra Help and Medicare Savings Program expansions were delayed
The law also postpones a planned expansion of Medicare assistance programs for lower-income beneficiaries until 2034.
The affected changes were part of a 2023 CMS rule intended to reduce barriers to enrollment in Medicare Savings Programs, which help eligible low-income Medicare beneficiaries with premiums and cost-sharing. The law prohibits implementation of certain provisions of that rule that had not yet taken effect until Oct. 1, 2034.
The law did not, however, delay the separate Extra Help program itself. Extra Help remains available to qualifying Medicare beneficiaries to help with prescription drug costs.
Resolve $10,000 or more of your debt
National Debt Relief could help you resolve your credit card debt with an affordable plan that works for you. Just tell them your situation, then find out your debt relief options.4 <p>Please note that all calls with the company may be recorded or monitored for quality assurance and training purposes. Clients who are able to stay with the program and get all their debt settled realize approximate savings of 45% before fees, or 20% including our fees, over 24 to 48 months. All claims are based on enrolled debts. Not all debts are eligible for enrollment. Not all clients complete our program for various reasons, including their ability to save sufficient funds. Estimates based on prior results, which will vary based on specific circumstances. We do not guarantee that your debts will be lowered by a specific amount or percentage or that you will be debt-free within a specific period of time. We do not assume consumer debt, make monthly payments to creditors or provide tax, bankruptcy, accounting or legal advice or credit repair services. Not available in all states. Please contact a tax professional to discuss tax consequences of settlement. Please consult with a bankruptcy attorney for more information on bankruptcy. Depending on your state, we may be available to recommend a local tax professional and/or bankruptcy attorney. Read and understand all program materials prior to enrollment, including potential adverse impact on credit rating. "Debt-Free" applies only to enrolled credit cards, personal loans, and medical bills. Not mortgages, car loans, or other debts. Results vary.</p>
Sign up for a free debt assessment here.
Nursing home staffing rules may not move forward
Another provision affects nursing home oversight. The law blocks implementation of new federal minimum staffing requirements that had been proposed for nursing homes participating in Medicare and Medicaid until 2034.
The 2024 federal rule included minimum staffing requirements for long-term care facilities. The new law prohibits the federal government from implementing, administering, or enforcing those minimum staffing levels until Oct. 1, 2034.
Dual-eligible seniors could face additional pressure
The law's Medicaid-related changes may also affect seniors who rely on both Medicare and Medicaid coverage. These beneficiaries are known as "dual eligibles."
An earlier CBO estimate for the House-passed version of the legislation projected that about 1.3 million fewer dual-eligible individuals would be enrolled in Medicaid in 2034. However, that estimate was based on the House-passed bill, and KFF notes that the number affected could be lower under the final enacted law.
These beneficiaries often depend on Medicaid to help cover services that Medicare does not fully pay for, including certain long-term care services and other health care costs.
Changes to Medicaid funding, eligibility, and enrollment could affect supplemental coverage in some states. The impact may vary depending on how states respond to the changes and how they implement the provisions.
The administration says core Medicare benefits remain protected
Administration officials have maintained that core Medicare benefits themselves remain intact under the law. Traditional Medicare eligibility, hospital coverage, and physician benefits have not been eliminated.
The OBBBA legislation focuses on broader fiscal and health care changes rather than directly eliminating standard Medicare coverage. However, the indirect effects of some Medicare and Medicaid provisions could still affect beneficiaries over time.
For retirees, the distinction between direct changes to Medicare benefits and changes affecting providers, drug pricing, or Medicaid assistance may matter.
Bottom line
The One Big Beautiful Bill Act (OBBBA) does not eliminate Medicare, but it changes several parts of the health care system that could matter to beneficiaries.
One of the biggest potential changes — the projected Medicare sequestration tied to Statutory PAYGO — was ultimately canceled after Congress reset the PAYGO scorecards. The previously projected $45 billion reduction in 2026 and roughly $536 billion through 2034 therefore did not take effect.
Other changes remain in place, including revisions to the orphan-drug exclusion from Medicare price negotiations, a delay affecting certain Medicare Savings Program rules, a delay in federal nursing home staffing requirements, and Medicaid changes that could affect some people who qualify for both Medicare and Medicaid.
Retirees may want to review their current Medicare coverage, prescription costs, and supplemental senior benefits carefully in the coming years. Staying informed about future rule changes could help you better prepare as Medicare and Medicaid policies continue evolving.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.


Intro Offer
INTRO OFFER: Unlimited Cashback Match for all new cardmembers. Discover will automatically match all the cash back you’ve earned at the end of your first year! There’s no minimum spending or maximum rewards. You could turn $150 cash back into $300
Annual Fee $0 Why we like it