



 Add Us On Google

51 is a significant milestone for many reasons, including as a checkpoint for your finances. Are you on track? Are you behind?
While each situation is different, we can share the Federal Reserve's most recent data on what others have saved up. Use it to review your own progress and measure how far you need to build real wealth and hit your ideal net worth number.
Set up direct deposit - pocket $400
Set up an eligible direct deposit with SoFi Checking and Savings and you could pocket a bonus of up to $400. Make the switch, set up direct deposit, earn the bonus. It basically takes no extra work at all other than following these steps.
Why people are switching: This account earns up to an insane 4.00% APY1 <p>Earn up to 4.00% Annual Percentage Yield (APY) on one SoFi Savings account with a 0.90% APY Boost (added to the 3.10% APY as of 5/28/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/26. Rates are variable, subject to change. Terms apply at <a href="https://www.sofi.com/banking/#4">sofi.com/banking#4</a>. SoFi Bank, N.A. Member FDIC.</p> on savings for up to six months (3.10% APY standard + 0.90% APY boost) on top of that $50 or $400 bonus.2 <p>New and existing Checking and Savings members who have not previously enrolled in Direct Deposit with SoFi are eligible to earn a cash bonus of either $50 (with at least $1,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more) OR $400 (with at least $5,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more). Cash bonus amount will be based on the total amount of Eligible Direct Deposit received within 25 calendar days of your first Eligible Direct Deposit of $1 or more. If you have satisfied the Eligible Direct Deposit requirements but have not received a cash bonus in your Checking account, please contact us at 855-456-7634 with the details of your Eligible Direct Deposit. Direct Deposit Promotion begins on 5/15/2026 and will be available through 12/31/26. See full bonus and annual percentage yield (APY) terms at <a href="https://www.sofi.com/banking/checking-offer/">sofi.com/banking/checking-offer/</a></p> That's way better than the measly 0.38% APY (as of 06/15/26)3 <p>Based on <a href="https://www.fdic.gov/national-rates-and-rate-caps">this</a> FDIC data, as of 6/15/26.</p> national average savings accounts offer.
No monthly fees and no surprises. Open your account and earn up to a $400 bonus
Median net worth for 51-year-olds
The Federal Reserve doesn't have a number specifically for age 51, but the 45-54 age bracket is a good starting point. The average household or family net worth for this age range is $971,270 and includes everything a household owns minus what it owes.
But the median number of $246,700 may be more meaningful than the average, since it shows half of households making more than $246,700, and half making less. The mean would be dramatically higher, since it's pulled up by very wealthy households, but may be less reasonable to compare yourself to.
What the trends tell us
One important takeaway may be that comparison-driven anxiety over net worth shouldn't revolve around numbers alone; someone isn't doing poorly just because they aren't hitting that almost million-dollar average.
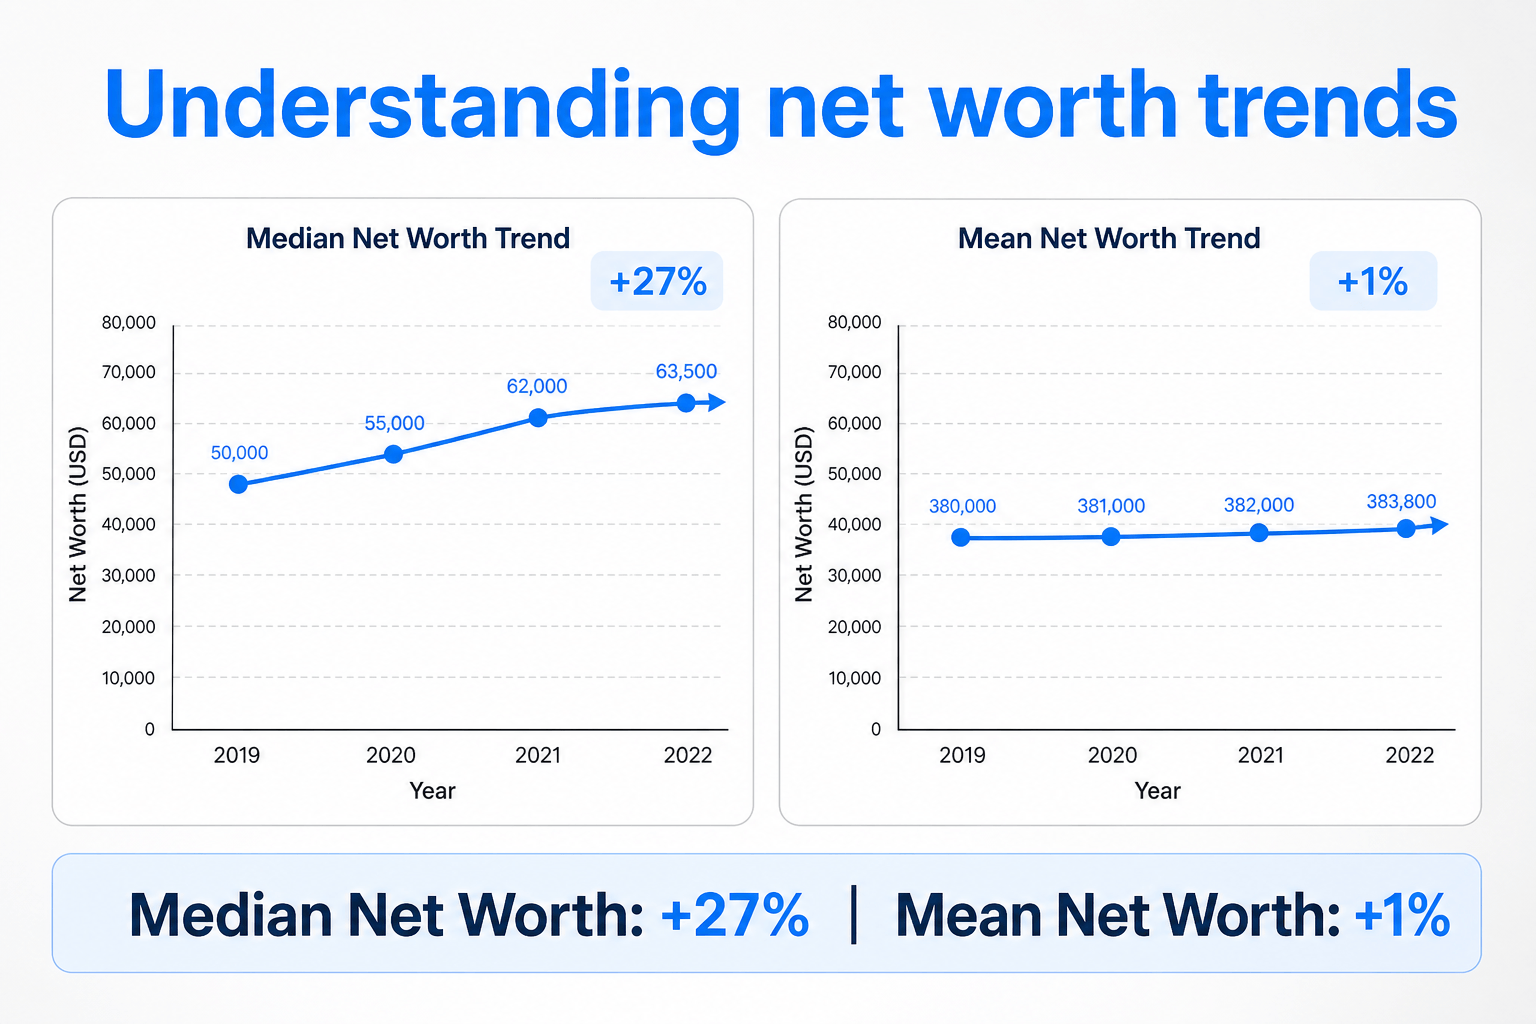
But perhaps more revealing than the "median vs. mean" data is how the numbers have changed over time. The median net worth for this age group increased 27% from 2019 to 2022, but the mean (average) only rose 1%.
Both figures are adjusted for inflation for that year's purchasing power and may show that net worth for the highest earners hasn't changed as much as it has for the rest of the population.
Peak earning years don't guarantee wealth
Households with a reference person in the 45-54 age bracket had the highest median before-tax family income of all the age groups in the report ($91,880). This was somewhat higher than the $86,470 for ages 35-44 and $82,150 for ages 55-64.
But income doesn't always translate into higher net worth, especially when expenses like paying for children's college costs, paying down mortgages, finishing up student loans, or caregiving for aging parents can eat into the budget. So, while income and net worth can be related, they don't typically move in lockstep.
Resolve $10,000 or more of your debt
National Debt Relief could help you resolve your credit card debt with an affordable plan that works for you. Just tell them your situation, then find out your debt relief options.4 <p>Please note that all calls with the company may be recorded or monitored for quality assurance and training purposes. Clients who are able to stay with the program and get all their debt settled realize approximate savings of 45% before fees, or 20% including our fees, over 24 to 48 months. All claims are based on enrolled debts. Not all debts are eligible for enrollment. Not all clients complete our program for various reasons, including their ability to save sufficient funds. Estimates based on prior results, which will vary based on specific circumstances. We do not guarantee that your debts will be lowered by a specific amount or percentage or that you will be debt-free within a specific period of time. We do not assume consumer debt, make monthly payments to creditors or provide tax, bankruptcy, accounting or legal advice or credit repair services. Not available in all states. Please contact a tax professional to discuss tax consequences of settlement. Please consult with a bankruptcy attorney for more information on bankruptcy. Depending on your state, we may be available to recommend a local tax professional and/or bankruptcy attorney. Read and understand all program materials prior to enrollment, including potential adverse impact on credit rating. "Debt-Free" applies only to enrolled credit cards, personal loans, and medical bills. Not mortgages, car loans, or other debts. Results vary.</p>
Sign up for a free debt assessment here.
Where wealth is usually held
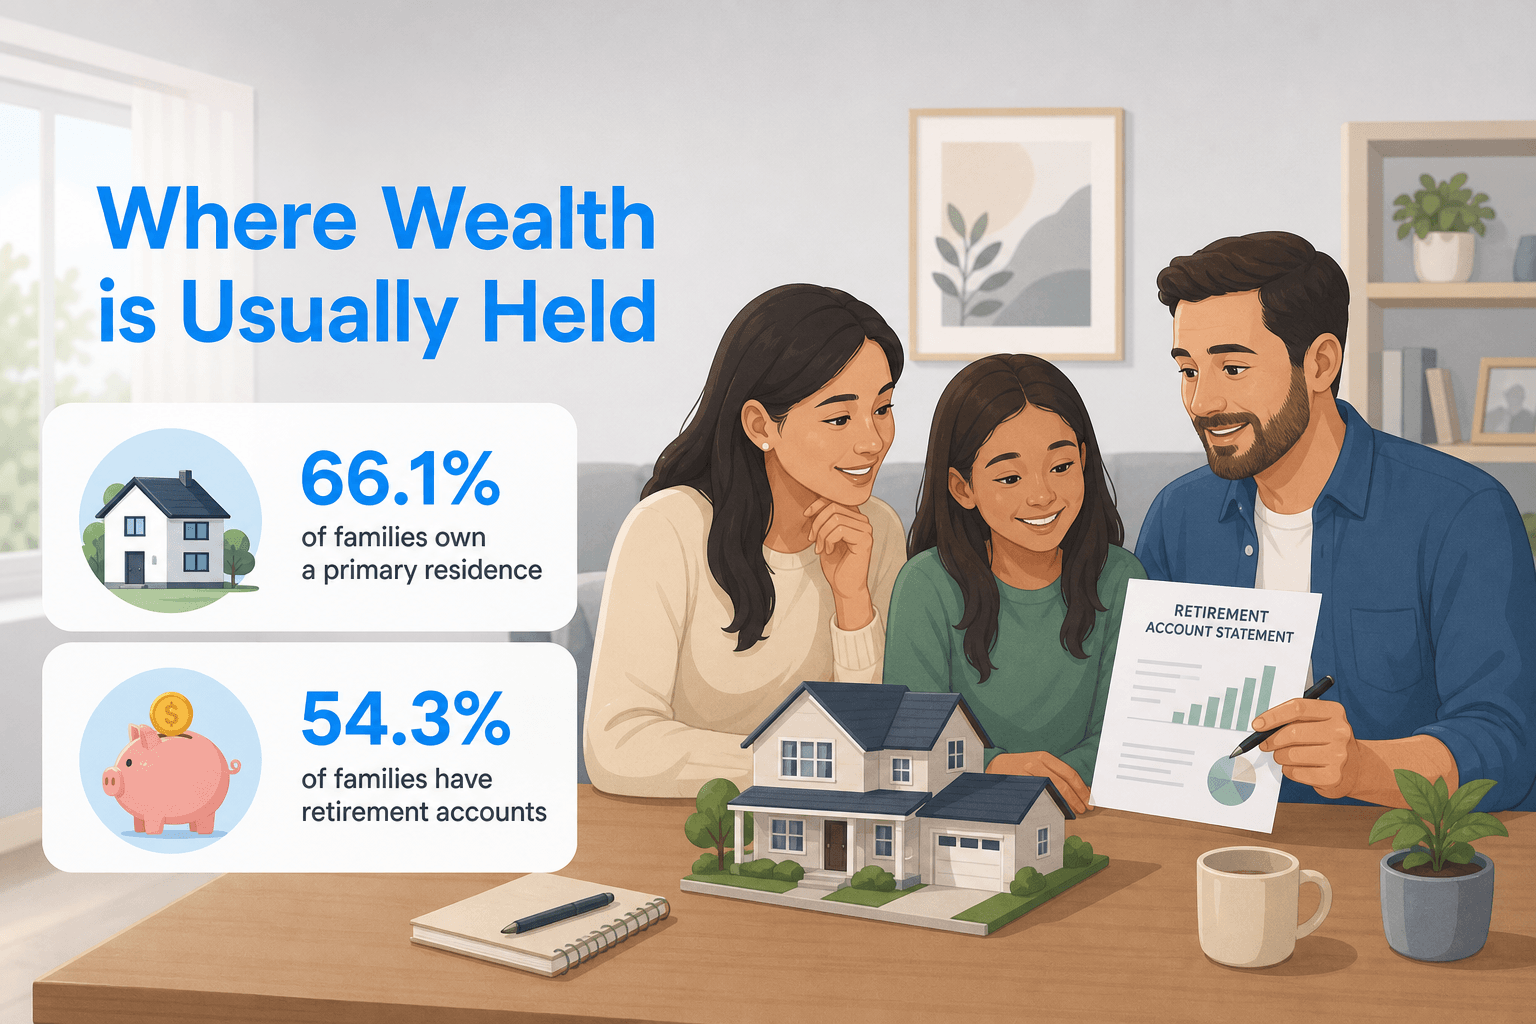
Net worth can include many asset types, so you can't assume that it's mainly liquid cash or stocks. Many middle-income households have their net worth tied up in homes or retirement accounts, something that's not easily accessible if they need it.
In 2022, 66.1% of all families owned a primary residence, and median net housing value was $201,000. Retirement accounts were also among the commonly held financial asset category, held by 54.3% of families. Among account holders, the median value was $86,900.
Liquid funds in transaction accounts like checking or savings were held by many, but the median balance was just $8,000.
How housing trends affect net worth
Rising home equity can have an outsized influence on balance sheets. An increase in home value due to inflation or rising home values in the surrounding area can raise net worth, even if the household hasn't truly experienced any more cash wealth.
For example, if your house suddenly has a new valuation that is $50,000 more than last year, your budgeting tool may reflect this in your final "net worth" metric. However, it's not new money you get to spend.
Why 50s matter so much
This age may be the final checkpoint to see if you're on track for retirement while you can still do something about it. It's very likely you're still working and can make continued contributions to your investments.
If you haven't done a net worth checkup in some time, start now. Add up all your assets, including vehicles, business interests, and liquid assets. Then, subtract liabilities, including any debt you owe on houses, cars, student loans, or credit cards.
Review this final number alongside monthly retirement contributions, high-interest debt, and expected required spending to see where you stand. Make sure you don't count home equity as spendable cash, even though it's included in your net worth figures.
Act now to boost savings rate
With your net worth number in hand, ask yourself, "Am I increasing my retirement contributions as my income rises?" rather than "Am I behind or ahead of the average net worth?"
The first question is more useful and helps you frame next steps:
- Check your employer match to maximize investments
- Review asset allocation and investment fees
- Pay down high-interest debt
- Build or fortify your emergency fund
- Update retirement income assumptions and beneficiaries
Each of these steps puts you in a better position for the future and can make your net worth progress more meaningful. If you need help, enlist a qualified financial advisor who can put these figures in context with your eventual retirement withdrawals and tax strategy.
Bottom line
$246,700 is the median net worth benchmark for households in the 45–54 age group, while $971,270 is the skewed average. But whether you more closely match the bigger number or the smaller one, it may be a less important metric for financial fitness than if you've established a healthy savings rate.
The share of gross income going toward retirement and other long-term savings matters, perhaps now more than ever. It's actionable, and unlike watching net worth numbers, measures a current habit you can adjust in real-time to ensure the next decade of financial decisions is more intentional.
FAQs
Is the median or average net worth more useful?
The median is generally a more realistic benchmark because extremely wealthy households can pull the average much higher. Still, neither figure determines whether you're personally prepared for retirement.
What should be included when calculating net worth?
Add the value of your assets, including savings, investments, retirement accounts, real estate, vehicles, and business interests. Then subtract liabilities such as mortgages, auto loans, student loans, and credit card balances.
What should I do if my net worth is below the median at age 51?
Focus on actions you can still control, such as capturing your full employer match, increasing retirement contributions, reducing high-interest debt, reviewing investment fees, and strengthening your emergency fund. A below-median net worth doesn't automatically mean you're behind because retirement needs vary considerably.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.


Intro Offer
INTRO OFFER: Unlimited Cashback Match for all new cardmembers. Discover will automatically match all the cash back you’ve earned at the end of your first year! There’s no minimum spending or maximum rewards. You could turn $150 cash back into $300
Annual Fee $0 Why we like it