





 Add Us On Google

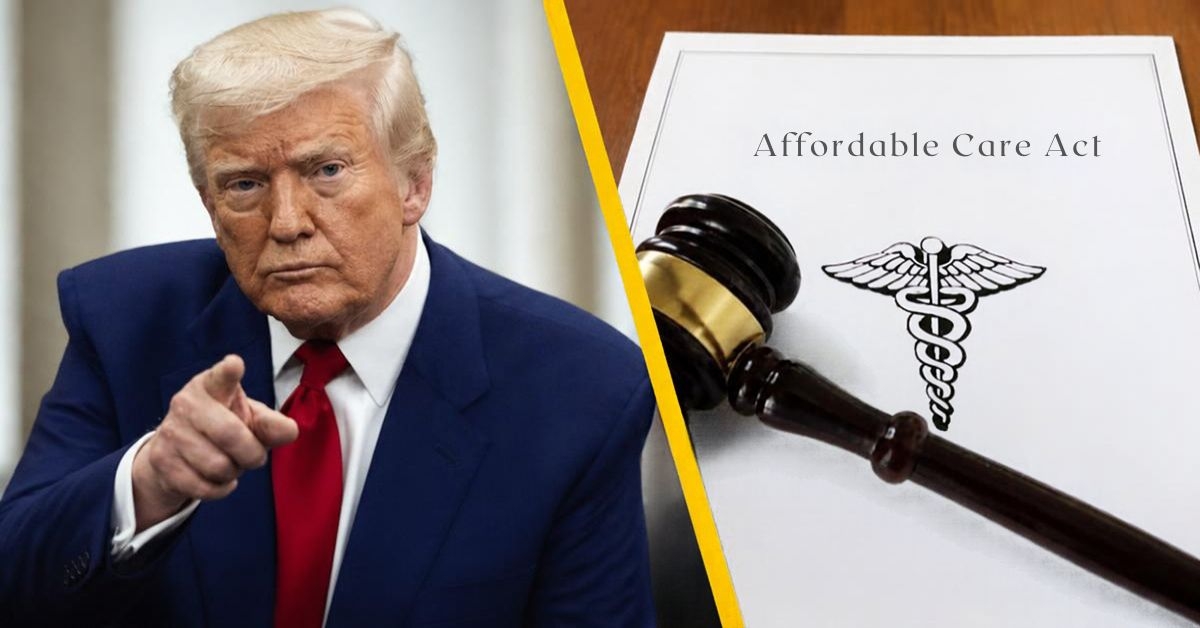
Health insurance has become more expensive for millions of Americans this year, particularly self-employed workers who buy their own coverage. Now, the Trump administration is working on a proposal that could give some of them another option.
The Labor Department is preparing a rule that could make it easier for trade groups and other associations to offer health insurance to their members. If finalized, the change could help some freelancers, gig workers, and small businesses save money on bills by banding together to buy coverage as a larger group.
Set up eligible direct deposit - pocket up to $400
Set up an eligible direct deposit with SoFi Checking and Savings and you could earn a bonus of $50 or $400.1 <p>New and existing Checking and Savings members who have not previously enrolled in Direct Deposit with SoFi are eligible to earn a cash bonus of either $50 (with at least $1,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more) OR $400 (with at least $5,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more). Cash bonus amount will be based on the total amount of Eligible Direct Deposit received within 25 calendar days of your first Eligible Direct Deposit of $1 or more. If you have satisfied the Eligible Direct Deposit requirements but have not received a cash bonus in your Checking account, please contact us at 855-456-7634 with the details of your Eligible Direct Deposit. Direct Deposit Promotion begins on 5/15/2026 and will be available through 12/31/2026. Full terms at <a href="https://www.sofi.com/banking/">sofi.com/banking</a>. SoFi Checking and Savings is offered through SoFi Bank, N.A., Member FDIC. SoFi members with Eligible Direct Deposit can earn 3.30% annual percentage yield (APY) on savings balances (including Vaults) and 0.50% APY on checking balances. There is no minimum Eligible Direct Deposit amount required to qualify for the 3.30% APY for savings (including Vaults). Members without Eligible Direct Deposit will earn 0.80% APY on savings balances (including Vaults) and 0.50% APY on checking balances. Interest rates are variable and subject to change at any time. These rates are current as of 9/23/26. Fees may reduce earnings. Additional information can be found at <a href="https://d32ijn7u0aqfv4.cloudfront.net/wp/wp-content/uploads/raw/SoFi-Bank-Rate-Sheet-September-23-2026.pdf">http://www.sofi.com/legal/banking-rate-sheet</a>.</p> Make the switch, set up eligible direct deposit, earn the bonus. It basically takes no extra work at all other than following these steps.
Why people are switching: This account earns up to an insane 4.20% APY2 <p>Earn up to 4.20% Annual Percentage Yield (APY) on one SoFi Savings account with a 0.90% APY Boost (added to the 3.30% APY as of 9/23/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/26. Rates are variable, subject to change. Terms apply at <a href="https://www.sofi.com/banking/#4">sofi.com/banking#4</a>. SoFi Bank, N.A. Member FDIC.</p> on savings for up to six months (3.30% APY standard + 0.90% APY boost) on top of that $50 or $400 bonus.1 <p>New and existing Checking and Savings members who have not previously enrolled in Direct Deposit with SoFi are eligible to earn a cash bonus of either $50 (with at least $1,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more) OR $400 (with at least $5,000 total Eligible Direct Deposits received within 25 calendar days of your first Eligible Direct Deposit of $1 or more). Cash bonus amount will be based on the total amount of Eligible Direct Deposit received within 25 calendar days of your first Eligible Direct Deposit of $1 or more. If you have satisfied the Eligible Direct Deposit requirements but have not received a cash bonus in your Checking account, please contact us at 855-456-7634 with the details of your Eligible Direct Deposit. Direct Deposit Promotion begins on 5/15/2026 and will be available through 12/31/2026. Full terms at <a href="https://www.sofi.com/banking/">sofi.com/banking</a>. SoFi Checking and Savings is offered through SoFi Bank, N.A., Member FDIC. SoFi members with Eligible Direct Deposit can earn 3.30% annual percentage yield (APY) on savings balances (including Vaults) and 0.50% APY on checking balances. There is no minimum Eligible Direct Deposit amount required to qualify for the 3.30% APY for savings (including Vaults). Members without Eligible Direct Deposit will earn 0.80% APY on savings balances (including Vaults) and 0.50% APY on checking balances. Interest rates are variable and subject to change at any time. These rates are current as of 9/23/26. Fees may reduce earnings. Additional information can be found at <a href="https://d32ijn7u0aqfv4.cloudfront.net/wp/wp-content/uploads/raw/SoFi-Bank-Rate-Sheet-September-23-2026.pdf">http://www.sofi.com/legal/banking-rate-sheet</a>.</p> That's way better than the measly 0.38% APY (as of 06/15/26)3 <p>Based on <a href="https://www.fdic.gov/national-rates-and-rate-caps">this</a> FDIC data, as of 6/15/26.</p> national average savings accounts offer.
No monthly fees and no surprises. Open your account and earn up to a $400 bonus
The proposal could expand association health plans
The Labor Department is developing a new rule that would establish when a group or association can qualify as an "employer" under the Employee Retirement Income Security Act, or ERISA, and sponsor an association health plan. The department submitted the proposal for White House review on July 23, although the draft itself has not been made public.
Association health plans allow multiple businesses to band together and buy health insurance as a larger group. In theory, a larger group may have more negotiating power and, depending on how the plan is structured, could also qualify for insurance rules that apply to larger employers.
The rule would set new requirements for which associations could offer association health plans (AHPs), although exactly which groups and workers would qualify remains unclear.
Self-employed workers may have the most to gain
The proposal could matter especially for freelancers, gig workers, and other people without employer coverage, as experts suggest it might help lower costs.
Many of these workers currently turn to the Affordable Care Act marketplace unless they have coverage through a spouse or another source. The enhanced Affordable Care Act (ACA) premium subsidies that had made marketplace coverage cheaper for millions of Americans expired at the end of 2025. People earning more than 400% of the federal poverty level were hit hard because many lost access to subsidies altogether.
KFF found that premium payments after tax credits rose an average of 58% among people who signed up for marketplace coverage in 2026. Some middle-income households also lost subsidies entirely and now face the full cost of their premiums.
Association plans could offer lower premiums
Supporters argue that AHPs could give workers without traditional employer coverage another way to lower their health care costs.
Pooling workers and small businesses into larger groups could lead to lower premiums for some people, particularly younger and healthier workers or those who earn too much to qualify for ACA subsidies. Still, a cheaper premium would only tell part of the story.
Resolve $10,000 or more of your debt
National Debt Relief could help you resolve your credit card debt with an affordable plan that works for you. Just tell them your situation, then find out your debt relief options.4 <p>Please note that all calls with the company may be recorded or monitored for quality assurance and training purposes. Clients who are able to stay with the program and get all their debt settled realize approximate savings of 45% before fees, or 20% including our fees, over 24 to 48 months. All claims are based on enrolled debts. Not all debts are eligible for enrollment. Not all clients complete our program for various reasons, including their ability to save sufficient funds. Estimates based on prior results, which will vary based on specific circumstances. We do not guarantee that your debts will be lowered by a specific amount or percentage or that you will be debt-free within a specific period of time. We do not assume consumer debt, make monthly payments to creditors or provide tax, bankruptcy, accounting or legal advice or credit repair services. Not available in all states. Please contact a tax professional to discuss tax consequences of settlement. Please consult with a bankruptcy attorney for more information on bankruptcy. Depending on your state, we may be available to recommend a local tax professional and/or bankruptcy attorney. Read and understand all program materials prior to enrollment, including potential adverse impact on credit rating. "Debt-Free" applies only to enrolled credit cards, personal loans, and medical bills. Not mortgages, car loans, or other debts. Results vary.</p>
Sign up for a free debt assessment here.
Cheaper coverage may come with trade-offs
A lower monthly premium doesn't necessarily mean a health plan provides the same coverage as an ACA marketplace policy.
Marketplace plans must cover the ACA's 10 essential health benefits, including prescription drugs, maternity care, and hospitalization. Some association plans treated as large-group coverage aren't subject to the same essential health benefit requirements. The Labor Department itself noted this distinction when it reviewed the previous AHP rule.
An AHP could therefore keep premiums lower by offering less comprehensive coverage, although federal protections against health-status discrimination would still apply. Workers would need to compare deductibles, provider networks, prescription coverage, and other benefits before deciding whether a plan is actually cheaper overall.
Lower premiums could mean higher costs for some
If AHPs attract disproportionately younger and healthier people away from the ACA marketplace, the remaining pool could become older or more expensive to insure. Insurers could then need to charge higher premiums to cover the medical costs of those who remain.
Health-policy experts have therefore warned that broader AHP access could raise marketplace costs, although the effect will depend on who becomes eligible and how many people switch.
Trump tried something similar in 2018
This is not the Trump administration's first attempt to expand association health plans. A 2018 Labor Department rule made it easier for groups to qualify as employers under ERISA and allowed some self-employed "working owners" without employees to participate.
Eleven states and the District of Columbia challenged the rule, and a federal court struck down key parts of it in 2019. The Biden administration later rescinded the rule in 2024.
That history could shape what happens this time. The Labor Department will have to decide how broadly it can expand eligibility without running into similar legal challenges.
What workers should watch next
The biggest thing to remember is that nothing about your health coverage changes yet. The proposal remains under White House review, and the Labor Department's regulatory agenda currently lists a proposed rule for November 2026. Even then, publication would begin the rulemaking process rather than immediately change the law.
Once the details are public, self-employed workers should watch whether sole proprietors are allowed to join, which associations qualify, what benefits AHPs must provide, and how premiums can vary among members.
Bottom line
The Trump administration's proposal could give some self-employed workers and small businesses another health insurance option at a time when ACA marketplace coverage has become more expensive.
Lower premiums may appeal to some workers, but coverage could be less comprehensive, and broader AHP enrollment could raise marketplace costs for others. With the full proposal still unpublished, the final rules will determine whether AHPs offer a better deal, which makes this a good time to check up on your financial health before comparing coverage options.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.


Intro Offer
INTRO OFFER: Unlimited Cashback Match for all new cardmembers. Discover will automatically match all the cash back you’ve earned at the end of your first year! There’s no minimum spending or maximum rewards. You could turn $150 cash back into $300
Annual Fee $0 Why we like it