Retirement Retired Life

8 Biggest Mistakes You Can Make in Your First Month of Retirement

Set yourself up for success by avoiding these common mistakes in the first 30 days of your retirement.

senior person writing notes and using laptop for planning
Updated March 20, 2025
Fact check checkmark icon Fact checked
Google Logo Add Us On Google info

To avoid wasting money in retirement, it's important to start this stage of your life on the right foot — and we don't just mean within the first year of you leaving the workforce. You can use the first 30 days of your official retirement to set the tone of the rest of your retirement, which makes it extra important to avoid making crucial money mistakes and start saving from day one.

Keep reading for our list of eight missteps to look out for within your first month of retired life.

Now Available: The Definitive Guide to Retirement Income

Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.

That is exactly what The Definitive Guide to Retirement Income helps answer.1 It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›

Not connecting with the people you want to stay in touch with from work

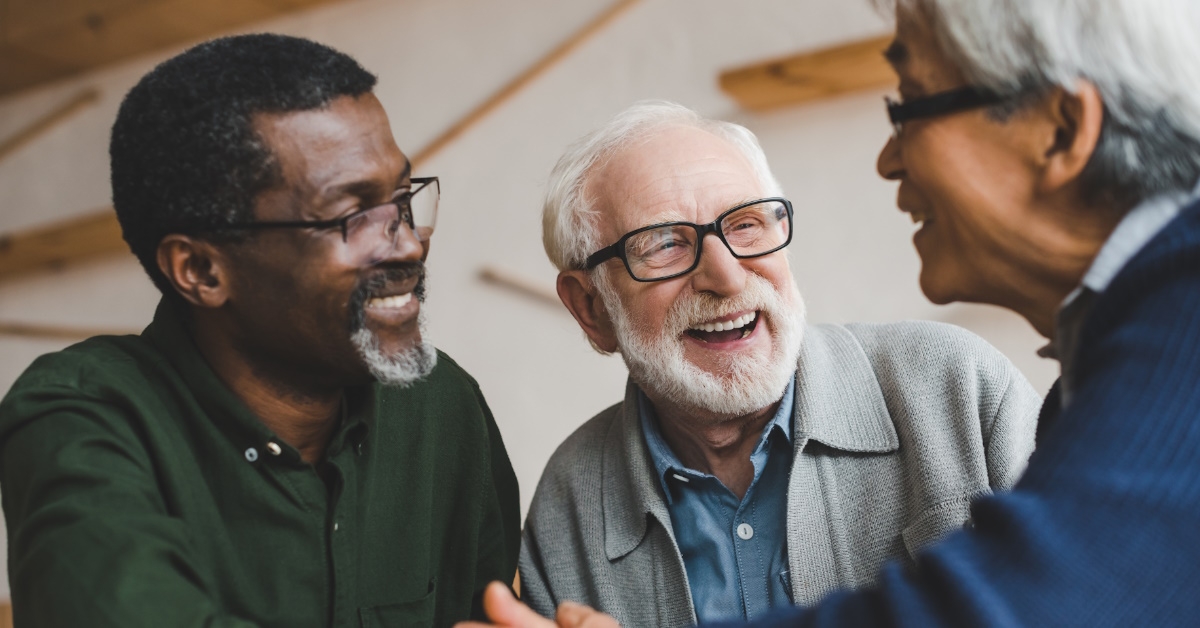
Rido/Adobe mature friends in conversation at home

Even once you're no longer socializing with coworkers in the breakroom, you can — and should — maintain relationships with friends from work.

For one thing, social isolation is a real phenomenon that can have big consequences on your physical and mental health. For another, you might want to pick up a part-time job to support your savings after you retire, and there's no better way to enter the job market than through a friendly recommendation.

Reaching out to your work friends within the first 30 days of your retirement will help establish your ongoing interest in the relationship and give you a chance to set up time to socialize outside of work.

Forgetting to cancel any automatic withdrawal for your prepaid parking/train pass

wichayada/Adobe woman using her phone on a sofa

One of the best parts of retiring is saving money on commuting expenses. Start lowering your bills right away by canceling any monthly subscriptions you used to streamline your commuter experience, from train passes to a prepaid downtown parking pass.

Waiting too long to set up your health insurance

Minerva Studio/Adobe health insurance

While you can enroll in Medicare as early as age 65, some people wait until they lose their employer-based health insurance to make the switch. Once you're no longer covered by your employer's health insurance, a Special Enrollment Period opens up so you can pick a Medicare plan.

However, if you fail to sign up during your enrollment period, you'll have to wait until next year's General Enrollment Period to sign up. Waiting this long results in a permanent penalty, meaning you'll pay more for Medicare for the rest of your life than you would have if you'd signed up immediately.

Signing up within the first 30 days of your retirement means you can cross this task off your mental checklist and start receiving health insurance benefits as soon as possible.

Released: The Definitive Guide to Retirement Income

Most people spend their entire working lives focusing on one thing: growing a pile of money. Then they retire and discover the skill they actually need is close to the opposite. Turning that pile into steady income, year after year, through good markets and bad, without ever running out. It may be the least discussed and most consequential transition in personal finance, and plenty of otherwise careful investors walk into it with no real plan.

That is exactly what The Definitive Guide to Retirement Income helps answer.1 It is a free guide from Fisher Investments covering what your retirement will really cost, where the cash flow should come from, and how much you can safely withdraw each year. Learn More Here ›

Not checking in with your partner about your retirement plans

bernardbodo/Adobe senior couple finalising budget for vacation

Hopefully, you and your spouse started discussing your retirement plans in depth well before you retired. But now that you've officially left the workforce, daily life might look a little different than it did when you were still talking in hypotheticals.

It's possible the two of you will need to make some changes to your plan — and talking about those changes sooner rather than later is better for your bottom line.

Make a point of checking in with your partner about how your retirement plan is going within the first 30 days so you don't waste any time (or money) trying to implement a plan that just won't work.

Withdrawing a large lump sum of money right away

Stockmachine/Adobe man holding american dollar bills

If you've been saving for retirement for decades, you probably have a tidy balance in your savings account and investment portfolios. It could be tempting to start eating into those funds immediately by withdrawing a large lump sum to take the vacation of your dreams.

But take a step back and consider the bigger picture. You need the money in your retirement account to last for decades, and the longer the money stays in your investment account, the more money you'll accrue on that principal.

Be smart about how much money you withdraw during this first month to set a smart precedent for the rest of your retirement.

Failing to structure your time right off the bat

insta_photos/Adobe older woman using smartphone sitting on couch at home

After a lengthy career, you deserve some unstructured time to relax and unwind. But be careful not to let that lack of structure become the norm. Otherwise, your sense of freedom could turn into listlessness fairly quickly.

While you don't need to overschedule yourself with social events and volunteer opportunities, make sure to pencil in a few tasks that will get you out of the house within the first month.

Making big spur-of-the-moment decisions

JackF/Adobe mature woman cutting metal profile using grinding machine

Now that you're experiencing the freedom you've spent decades dreaming about, you might be tempted to make some huge lifestyle changes without a job to hold you back.

But, moving across the country, booking a months-long global vacation, or completely remodeling your home are all big financial decisions that shouldn't be made off the cuff in a wild burst of enthusiasm.

Reigning yourself in during this first month of a job-free life requires some self-control, but your wallet will thank you for waiting to make smart, reasoned decisions that match your budgeting goals.

Throwing yourself back into the workforce immediately

Ivan Traimak/Adobe elderly businesswoman with a laptop

If you're a worrier by nature, you might start getting anxious about your retirement savings balance sooner than later. While picking up another job is a solid way to supplement your retirement savings, it's okay to give yourself a break after your retirement.

Even if you go back to work within a month or two, enjoy a little time to yourself first. Remember, retirement is a long game, and you don't want to burn out too early on.

Bottom line

insta_photos/Adobe old woman working from home using laptop and taking notes

Setting yourself up for a stress-free retirement is a process that starts while you're still working and saving, but it doesn't stop just because you've left your job behind. Instead, make an ongoing commitment to spend wisely, continue to save, and avoid costly mistakes that could make for a less-than-ideal retirement.

If you can proactively take positive steps right away, you'll be better able to enjoy the hard-earned time off you deserve after your long career.

AARP Benefits
  • Huge discounts on travel, groceries, prescriptions and more
  • Access to financial planning resources and health tools
  • Join AARP and get 25% off with automatic renewal


Financebuzz logo

Thanks for subscribing!

Please check your email to confirm your subscription.